
Foreign Direct Investments in Kenya, & Cytonn Weekly #45.2026
By Research Team, Nov 15, 2026
Executive Summary
Fixed Income
During the week, T-bills were oversubscribed for the fifteenth consecutive week, with the overall subscription rate increasing to 247.3%, from 241.8% recorded the previous week. Investors’ preference for the shorter 91-day paper persisted, with the paper receiving bids worth Kshs 31.7 bn against the offered Kshs 8.0 bn, translating to a subscription rate of 396.1%, lower than the subscription rate of 431.2% recorded the previous week. The subscription rates for the 182-day and 364-day papers increased to 223.3% and 152.4%, from 218.9% and 113.1% recorded the previous week, respectively. The government accepted a total of Kshs 56.7 bn worth of bids out of Kshs 69.3 bn bids received, translating to an acceptance rate of 81.9%. The yields on the government papers were on a downward trajectory, with the yield on the 364-day paper decreasing the most by 1.8 bps to 9.01% from 9.03% recorded the previous week, while the yields on the 182-day and 91-day papers decreased by 0.8 bps and 0.5 bps to 8.84% and 8.74%, respectively, from 8.85% and 8.75% recorded the previous week;
During the week, the Central Bank of Kenya released the auction results for the switch of treasury bonds and the treasury bills. The securities being switched from were T-Bills 2696/091, 2657/182 and 2585/364, and FXD1/2023/005, to FXD4/2019/010, which has tenor to maturity of 3.0 years and a fixed coupon rate of 12.3%. The bond was undersubscribed, with the overall subscription rate coming in at 37.9%, receiving bids worth Kshs 3.8 bn against the offered Kshs 10.0 bn. The government accepted all bids worth Kshs 3.8 bn, translating to an acceptance rate of 100.0%. Non-competitive bids accounted for 77.7% of the accepted amount at Kshs 2.9 bn, with competitive bids at Kshs 843.3 mn. The weighted average yield for the accepted bids for the FXD4/2019/010 came in at 11.2%, below the 12.3% coupon, with the bond priced at a premium of Kshs 108.6 per Kshs 100. With the inflation rate at 7.3% as of October 2026, the real return of the FXD4/2019/010 was 3.9%. Given the 10.0% withholding tax on the bonds, the tax equivalent yield for shorter term bonds with 15.0% withholding tax is 11.9% for the FXD4/2019/010;
Also, during the week, the government announced a prospectus for the re-opening of two Treasury bonds, FXD1/2019/015 and SDB1/2011/030, seeking to raise Kshs 50.0 bn for budgetary support. The 15-year FXD1/2019/015 carries a fixed coupon rate of 12.9% and a remaining tenor to maturity of 7.3 years, while the 30-year SDB1/2011/030 carries a fixed coupon rate of 12.0% and a remaining tenor to maturity of 14.3 years. The sale period opened on 10th November 2026 and closes on 18th November 2026 (bids due by 10.00am), with the auction and settlement dates set for 18th and 23rd November 2026, respectively. Both bonds are sold through a multi-price bid auction and attract a 10% withholding tax. Our recommended bidding ranges are 11.9%-12.4% for FXD1/2019/015 and 12.4%-13.2% for SDB1/2011/030.
During the week, the Energy and Petroleum Regulatory Authority (EPRA) released their monthly statement on the maximum retail fuel prices in Kenya, effective from 15th November 2026 to 14th December 2026. Notably, the maximum allowed prices for Kerosene, Super Petrol and Diesel remained unchanged at Kshs 219.9, Kshs 227.0 and Kshs 227.8 per litre, respectively, as the Government applied Kshs 4.6 bn from the Petroleum Development Levy Fund to stabilize prices;
Equities
During the week, the equities market was on an upward trajectory, with the NSE 10, NSE 25, NASI, and NSE 20 increasing by 1.7%, 1.3%, 0.8%, and 0.03% respectively, taking their YTD performance to gains of 35.2%, 33.4%, 33.2%, and 29.0% for NSE 10, NSE 20, NSE 25 and NASI respectively. The week-on-week equities market performance was mainly driven by gains recorded by large-cap stocks such as Co-operative, Absa, and Stanbic of 7.9%, 3.7%, and 2.3% respectively. The performance was however weighed down by losses recorded by large-cap stocks such as BAT, NCBA, and KCB of 2.0%, 0.8%, and 0.6% respectively;
During the week, the banking sector index increased by 1.5% to 284.1 from the 279.8 recorded the previous week. This is attributable to gains recorded by large cap stocks such as Co-operative, Absa, and Stanbic of 7.9%, 3.7%, and 2.3% respectively. The performance was however weighed down by losses recorded by large-cap stocks such as NCBA, KCB and DTBK of 0.8%, 0.6% and 0.4% respectively;
During the week, equities turnover decreased by 96.3% to USD 31.0 mn from USD 846.7 mn recorded the previous week, taking the YTD total turnover to USD 4,348.3 mn. Foreign investors became net sellers for the first time in two weeks with a net selling position of USD 2.4 mn, from a net buying position of USD 820.2 mn recorded the previous week, taking the YTD foreign net buying position to USD 620.3 mn, compared to a net selling position of USD 92.9 mn recorded in 2025;
During the week, Co-op Bank released their Q3’2026 financial results, recording a 27.2% increase in profit after tax to Kshs 27.4 bn in Q3’2026, from Kshs 21.6 bn in Q3’2025;
Real Estate
During the week, Hass Consult, a Kenyan consulting and Real Estate development firm, released its Land and property Price Indices Q3'2026 Report, highlighting the performance of the Real Estate land and property sectors in the Nairobi Metropolitan Area (NMA);
During the week, Cirium’s global aviation rankings placed Kenya Airways (KQ) sixth in Africa by traffic, as its revenue passenger kilometres declined by 18.2% to 9,982 mn in 2025 from 12,204 mn in 2024, on capacity constraints from grounded aircraft, with the Kshs 45.4 bn government support to restore its fleet expected to gradually rebuild capacity;
On the Unquoted Securities Platform Acorn D-REIT and I-REIT traded at Kshs 29.7 and Kshs 24.4 per unit, respectively, as per the last updated data on 30th October 2026. The performance represented a 48.3% and 22.2% gain for the D-REIT and I-REIT, respectively, from the Kshs 20.0 inception price. The volumes traded during the week for the D-REIT and I-REIT came in at 49,228 and 425,844 units, respectively. Additionally, ILAM Fahari I-REIT closed at Kshs 13.8 per unit as of 30th October 2026, representing a 31.0% loss from the Kshs 20.0 inception price, with no trades recorded during the week;
Digital Payments Weekly Highlights
During the week, Circle Internet Group announced a multi-year partnership with Global Citizen to expand digital financial access and economic opportunities across Africa, beginning with the Move Afrika initiative. Starting in Rwanda in 2027, the partnership will introduce USDC payments for participating vendors and suppliers, with the aim of reducing transaction costs, accelerating settlement and improving access to international commerce;
During the week, Global Payments Inc. announced the expansion of its AI powered Adaptive Authentication platform through the integration of Visa Intelligent Data Exchange (IDX) API, initially supporting eligible domestic transactions in the United States and Canada. The enhancement enables merchants to share richer transaction data with issuers to improve authorization decisions, increase approval rates and reduce false declines and unnecessary customer authentication challenges;
The digital payment stocks we track (AXP, Visa, Mastercard, Circle, Block, PayPal and Global Payments) are currently trading at an average forward P/E of 25.8x, implying that investors continue to price in resilient earnings growth and strong digital payment adoption, although elevated operating costs and higher client incentives across legacy card networks may moderate valuation expansion in the near term.
Focus of the Week
In an increasingly interconnected global economy, Foreign Direct Investments (FDIs) serve as a pivotal conduit for economic growth, innovation, and integration, and have emerged as a key indicator of a country’s economic attractiveness and competitiveness. According to the United Nations Conference on Trade and Development (UNCTAD) World Investment Report 2026, global FDI inflows rose 6.0% in 2025 to USD 1.6 tn, from USD 1.5 tn in 2024. Inflows to developed economies grew 11.5% to USD 723.5 bn from USD 649.1 bn, while developing economies grew only 2.0% to USD 900.8 bn from USD 882.6 bn, and the top 20 host economies took more than 80.0% of global FDI. Excluding conduit flows through major European financial centers, global FDI grew 4.0%. UNCTAD also warns that the 2026 Middle East escalation is a major adverse shock to the global investment environment, through higher costs, greater uncertainty and tighter financial conditions. Africa moved the opposite way. Inflows fell by 26.3% to USD 69.5 bn from an exceptional USD 94.3 bn in 2024. That was a base effect, as 2025 was still the third-highest year since 1990. Kenya bucked the continental trend. FDI inflows rose 37.7% to a record USD 3,200.0 mn in 2025, from USD 2,324.0 mn in 2024. Kenya remains East Africa’s third-largest recipient, behind Ethiopia and Uganda.
Investment Updates:
-
Weekly Rates: Cytonn Money Market Fund closed the week at a yield of 11.09% p.a. To invest, dial *809# or download the Cytonn App from Google Play store here or from the Appstore here;
-
We continue to offer Wealth Management Training every Tuesday, from 7:00 pm to 8:00 pm. The training aims to grow financial literacy among the general public. To register for any of our Wealth Management Trainings, click here; If interested in our Private Wealth Management Training for your employees or investment group, please get in touch with us through wmt@cytonn.com;
-
Cytonn Asset Managers Limited (CAML) continues to offer pension products to meet the needs of both individual clients who want to save for their retirement during their working years and Institutional clients that want to contribute on behalf of their employees to help them build their retirement pot. To learn more about our pension schemes, kindly get in touch with us through pensions@cytonn.com;
Hospitality Updates:
-
We currently have promotions for Staycations. Visit cysuites.com/offers for details or email us at sales@cysuites.com;
Money Markets, T-Bills Primary Auction:
This week, T-bills were oversubscribed for the fifteenth consecutive week, with the overall subscription rate increasing to 247.3%, from 241.8% recorded the previous week. Investors’ preference for the shorter 91-day paper persisted, with the paper receiving bids worth Kshs 31.7 bn against the offered Kshs 8.0 bn, translating to a subscription rate of 396.1%, lower than the subscription rate of 431.2% recorded the previous week. The subscription rates for the 182-day and 364-day papers increased to 223.3% and 152.4%, from 218.9% and 113.1% recorded the previous week, respectively. The government accepted a total of Kshs 56.7 bn worth of bids out of Kshs 69.3 bn bids received, translating to an acceptance rate of 81.9%. The yields on the government papers were on a downward trajectory, with the yield on the 364-day paper decreasing the most by 1.8 bps to 9.01% from 9.03% recorded the previous week, while the yields on the 182-day and 91-day papers decreased by 0.8 bps and 0.5 bps to 8.84% and 8.74%, respectively, from 8.85% and 8.75% recorded the previous week.
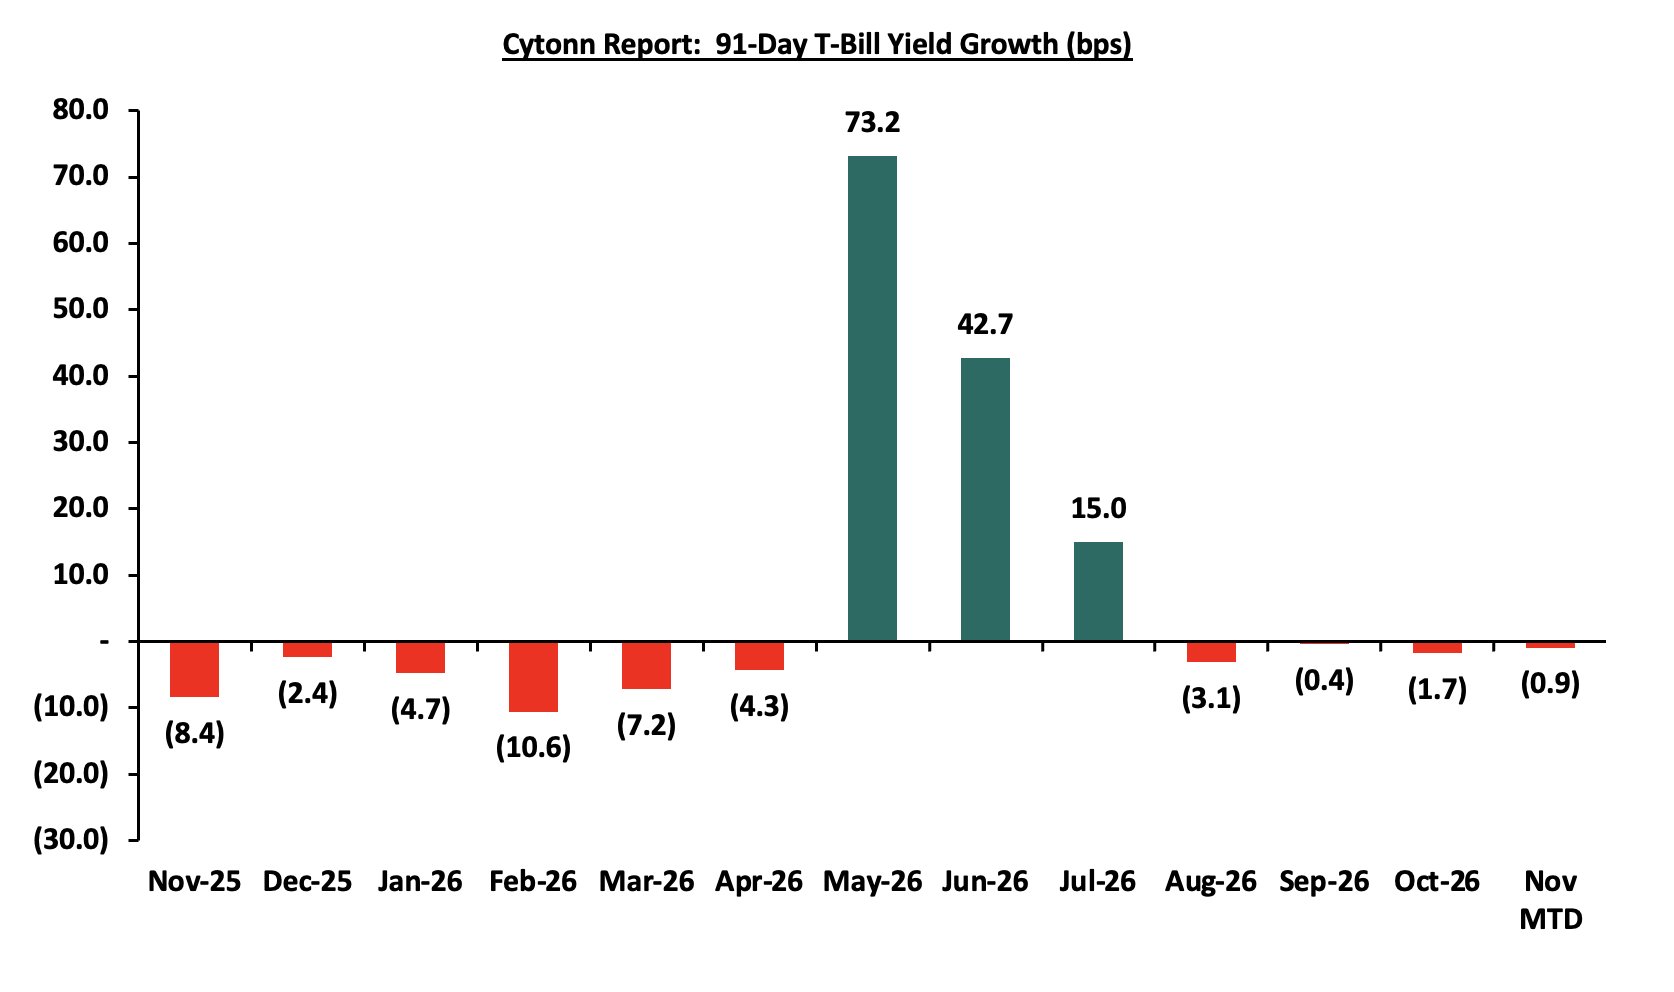
The chart below shows the yield growth rate for the 91-day paper from Nov 2025 to date:
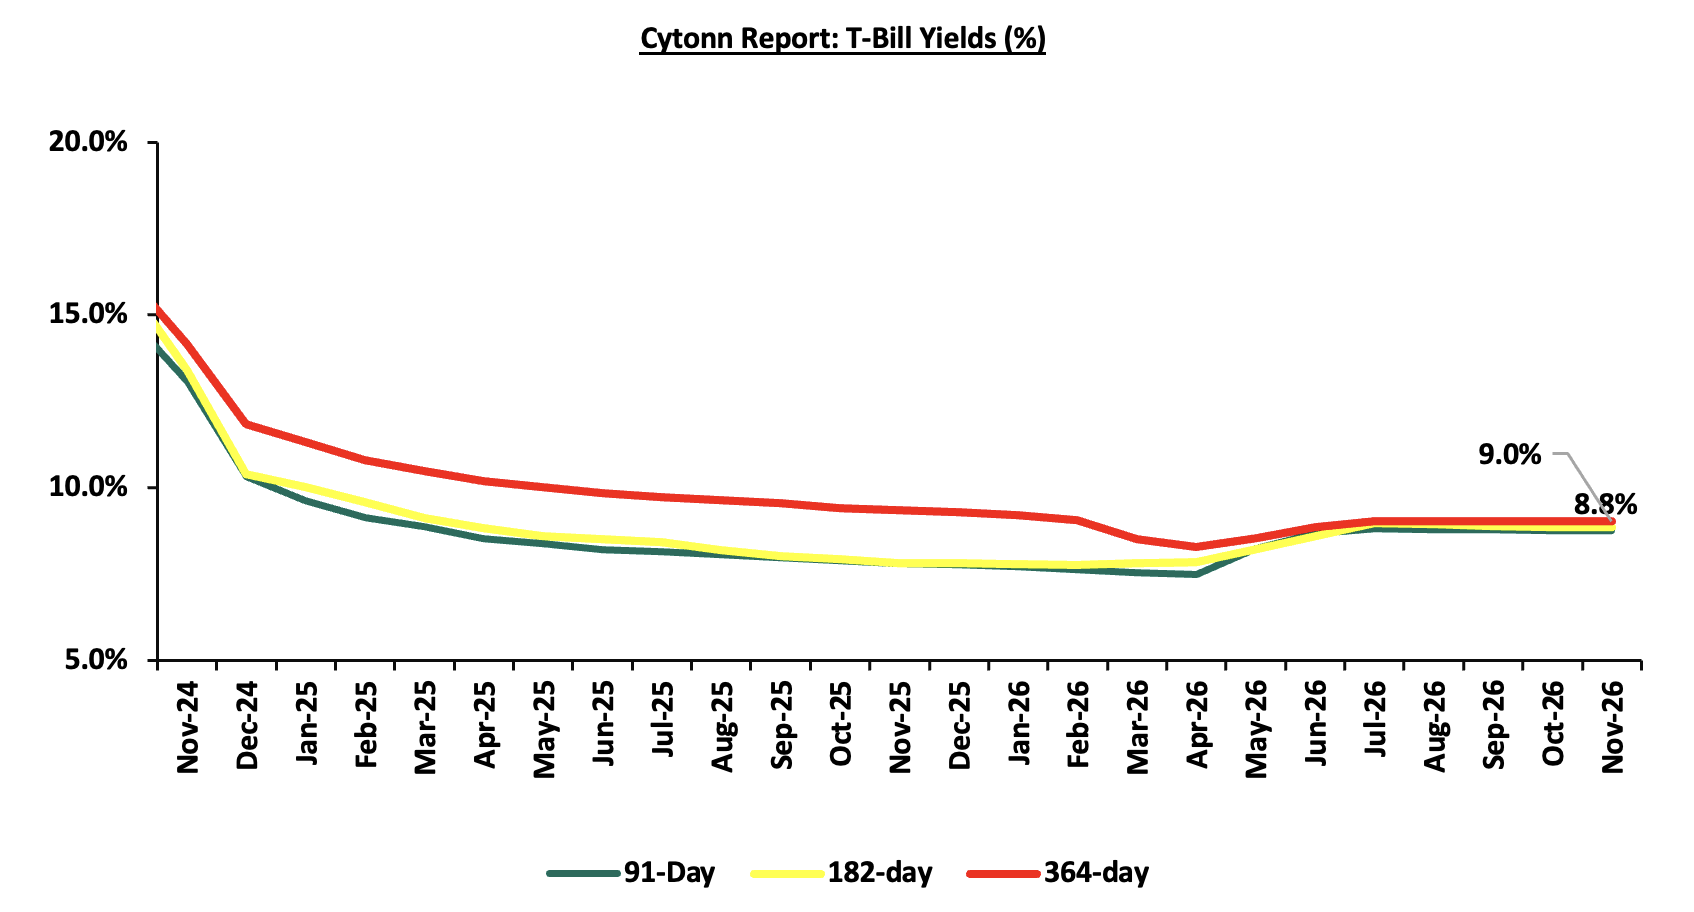
The chart below shows the performance of the 91-day, 182-day and 364-day papers from November 2024 to November 2026:
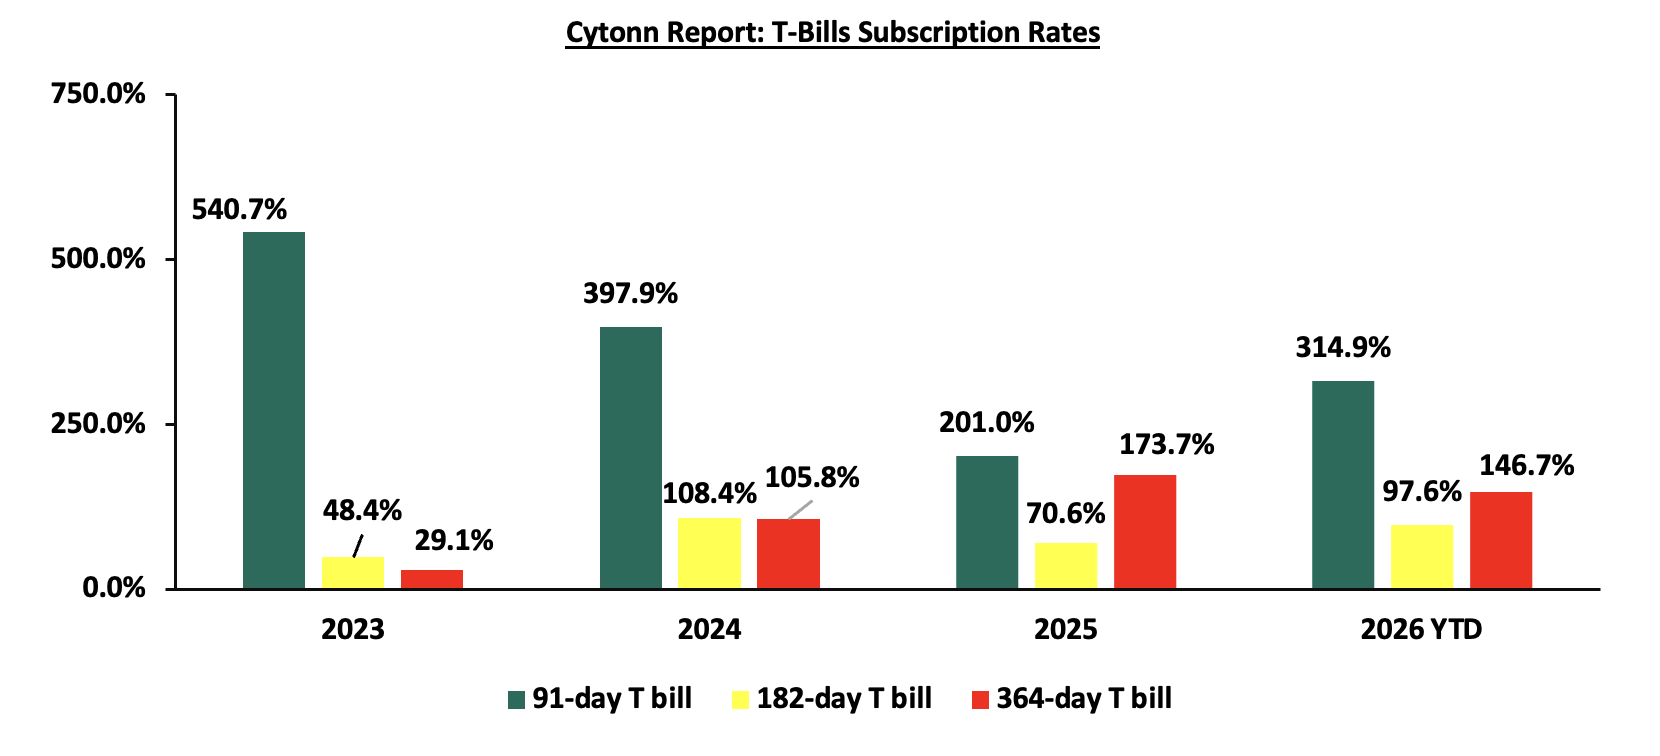
The chart below compares the overall average T-bill subscription rates obtained in 2023, 2024, 2025 and 2026 Year-to-date (YTD):
T-Bonds Primary Auction:
During the week, the Central Bank of Kenya released the auction results for the switch of treasury bonds and bills. The switch was from T-Bills 2696/091, 2657/182 and 2585/364, and FXD1/2023/005, to FXD4/2019/010, with a tenor to maturity of 3.0 years and a fixed coupon rate of 12.3%. The bond was undersubscribed, with the overall subscription rate coming in at 37.9%, receiving bids worth Kshs 3.8 bn against the offered Kshs 10.0 bn. The government accepted all bids worth Kshs 3.8 bn, translating to an acceptance rate of 100.0%. Non-competitive bids accounted for 77.7% of the accepted amount at Kshs 2.9 bn, with competitive bids at Kshs 843.3 mn. The weighted average yield for the accepted bids for the FXD4/2019/010 came in at 11.2%, below the 12.3% coupon, with the bond priced at a premium of Kshs 108.6 per Kshs 100. With the inflation rate at 7.3% as of October 2026, the real return of the FXD4/2019/010 was 3.9%. Given the 10.0% withholding tax on the bonds, the tax equivalent yield for shorter term bonds with 15.0% withholding tax is 11.9% for the FXD4/2019/010.
Also, during the week, the government announced a prospectus for the re-opening of two Treasury bonds, FXD1/2019/015 and SDB1/2011/030, seeking to raise Kshs 50.0 bn for budgetary support. The 15-year FXD1/2019/015 carries a fixed coupon rate of 12.9% and a remaining tenor to maturity of 7.3 years, while the 30-year SDB1/2011/030 carries a fixed coupon rate of 12.0% and a remaining tenor to maturity of 14.3 years. The sale period opened on 10th November 2026 and closes on 18th November 2026, with the auction and settlement dates set for 18th and 23rd November 2026, respectively. Both bonds are sold through a multi-price bid auction and attract a 10% withholding tax. Our recommended bidding ranges are 11.9%-12.4% for FXD1/2019/015 and 12.4%-13.3% for SDB1/2011/030.
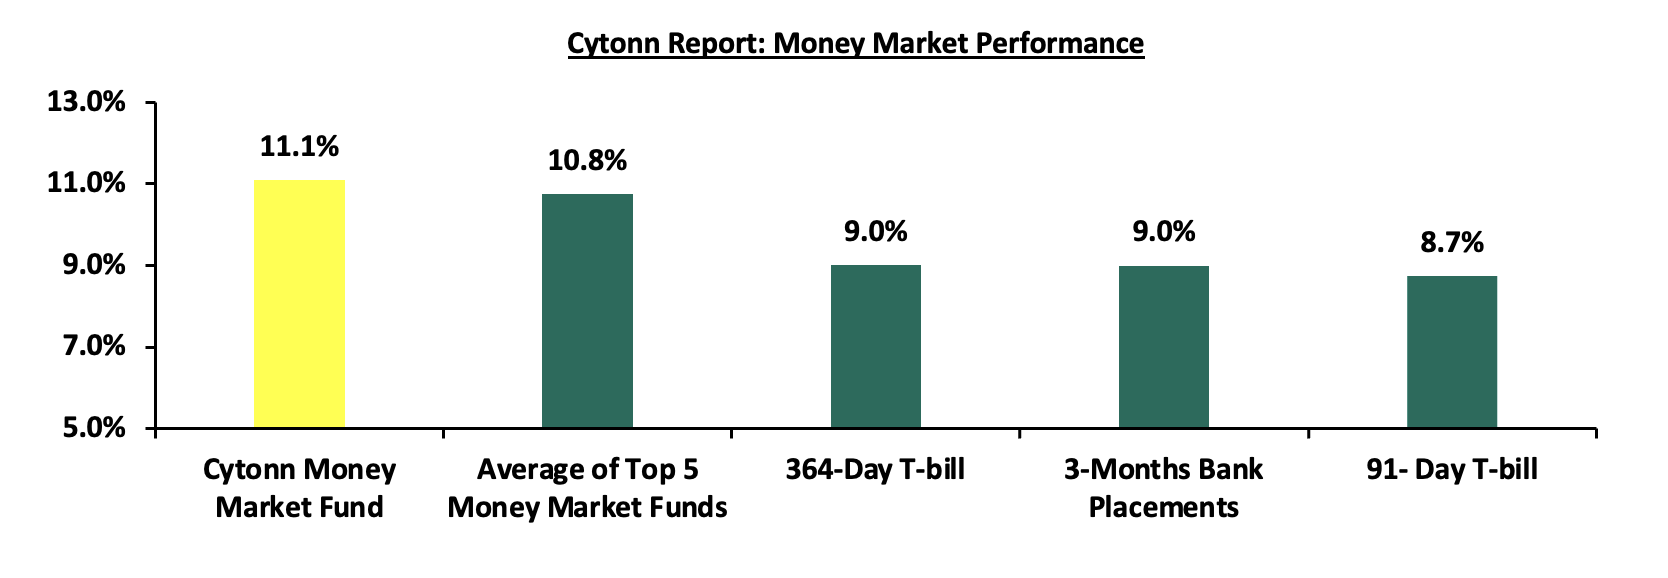
In the money markets, 3-month bank placements ended the week at 9.0% (based on rates offered by various banks). The yields on the government papers declined marginally, with the yield on the 91-day paper decreasing by 0.5 bps to 8.74% from 8.75% recorded the previous week, while the yields on the 364-day papers decreased by 1.8 bps, to 9.01% from 9.03% recorded the previous week. The yield on the Cytonn Money Market Fund remained relatively unchanged from the 11.1% recorded the previous week, while the average yields on Top 5 Money Market Funds increased by 7.2 bps to 10.76% from 10.69% recorded the previous week.
The table below shows the Money Market Fund Yields for Kenyan Fund Managers as published on 13th November 2026
|
Money Market Fund Yield for Fund Managers as published on 13th November 2026 |
||
|
Rank |
Fund Manager |
Effective Annual Rate |
|
1 |
Cytonn Money Market Fund ( Dial *809# or download Cytonn App) |
11.1% |
|
2 |
Faulu Money Market Fund |
10.9% |
|
3 |
Nabo Africa Money Market Fund |
10.7% |
|
4 |
Lofty-Corban Money Market Fund |
10.6% |
|
5 |
Ndovu Money Market Fund |
10.5% |
|
6 |
Rejesha Money Market Fund |
10.5% |
|
7 |
Orient Kasha Money Market Fund |
10.3% |
|
8 |
Old Mutual Money Market Fund |
10.3% |
|
9 |
Arvocap Money Market Fund |
10.3% |
|
10 |
Etica Money Market Fund |
10.3% |
|
11 |
Enwealth Money Market Fund |
10.3% |
|
12 |
Kuza Money Market fund |
10.2% |
|
13 |
Madison Money Market Fund |
10.2% |
|
14 |
Gulfcap Money Market Fund |
10.1% |
|
15 |
Jubilee Money Market Fund |
10.1% |
|
16 |
GenAfrica Money Market Fund |
10.1% |
|
17 |
Apollo Money Market Fund |
9.6% |
|
18 |
Globetec Money Market Fund |
9.6% |
|
19 |
SanlamAllianz Money Market Fund |
9.6% |
|
20 |
British-American Money Market Fund |
9.4% |
|
21 |
Dry Associates Money Market Fund |
9.2% |
|
22 |
KCB Money Market Fund |
9.2% |
|
23 |
Genghis Money Market Fund |
8.9% |
|
24 |
CPF Money Market Fund |
8.8% |
|
25 |
CIC Money Market Fund |
8.4% |
|
26 |
AA Kenya Shillings Fund |
8.3% |
|
27 |
Mali Money Market Fund |
8.3% |
|
28 |
Mayfair Money Market Fund |
8.2% |
|
29 |
Co-op Money Market Fund |
8.0% |
|
30 |
ICEA Lion Money Market Fund |
7.9% |
|
31 |
Absa Shilling Money Market Fund |
7.3% |
|
32 |
Ziidi Money Market Fund |
6.1% |
|
33 |
Stanbic Money Market Fund |
5.9% |
|
34 |
Equity Money Market Fund |
5.5% |
Source: Business Daily
Liquidity:
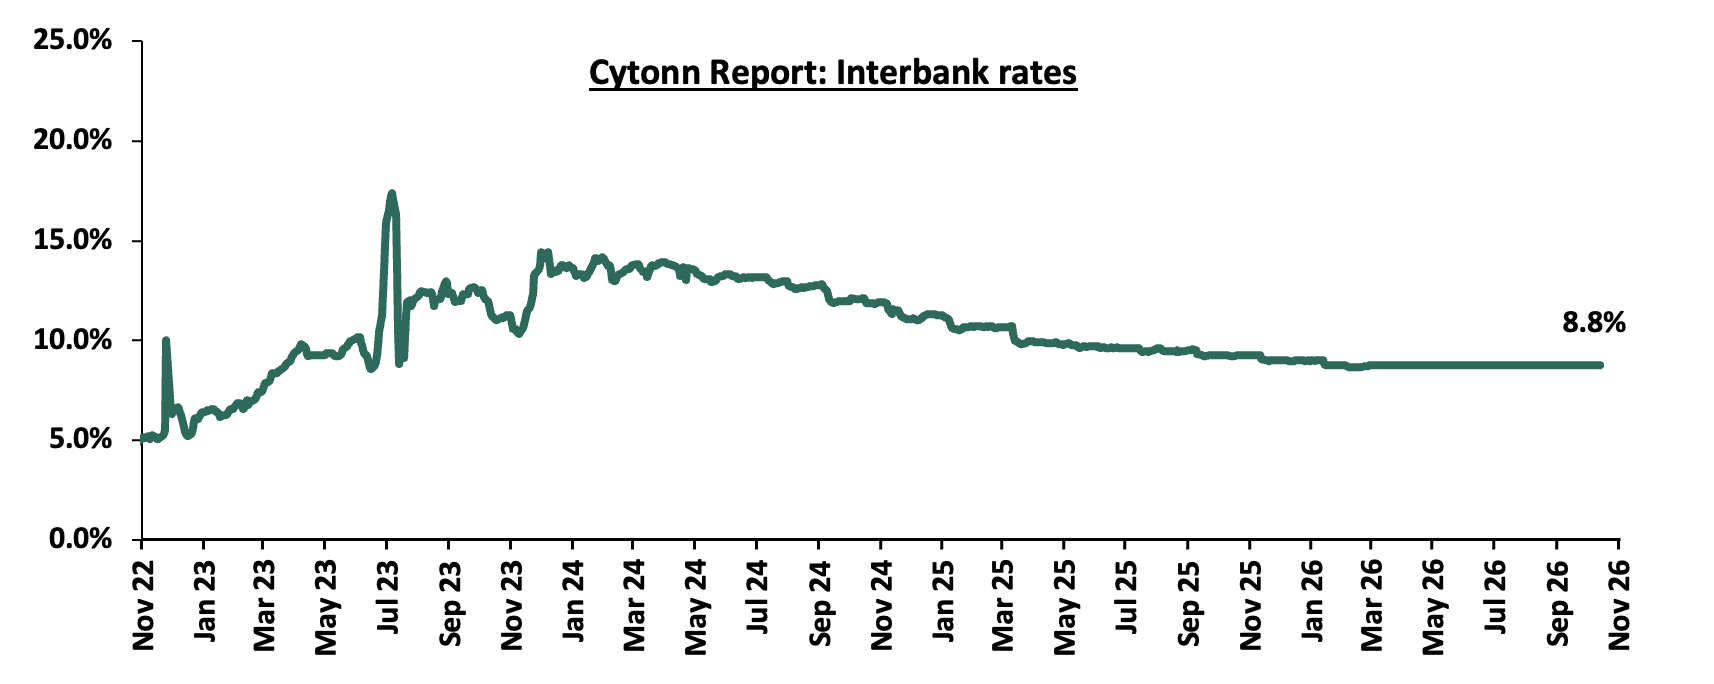
During the week, liquidity in the money markets remained relatively stable, with the average interbank rate increasing marginally by 0.04 bps to remain at 8.75%, unchanged from the previous week, partly attributable to tax payments that offset government payments. The average interbank volumes traded increased by 45.4% to Kshs 13.4 bn from Kshs 9.2 bn recorded the previous week. The chart below shows the interbank rates in the market over the years:
Kenya Eurobonds:
During the week, the yields on the Eurobonds registered a mixed performance with the 10- year issued in 2018 increased the most by 11.4 bps to 7.2% from 7.1% recorded the previous week while the yields on the 13 -year issued in 2021 decreased the most by 12.3 bps to 8.9% from 9.0% recorded the previous week. The table below shows the summary performance of the Kenyan Eurobonds as of 13th November 2026:
|
Cytonn Report: Kenya Eurobonds Performance |
||||||
|
|
2018 |
2019 |
2021 |
2024 |
||
|
Tenor |
10-year issue |
30-year issue |
12-year issue |
13-year issue |
7-year issue |
|
|
Amount Issued (USD) |
1.0 bn |
1.0 bn |
1.0 bn |
1.5 bn |
1.5 bn |
|
|
Years to Maturity |
1.3 |
21.3 |
8.8 |
5.5 |
10.5 |
|
|
Yields at Issue |
7.3% |
8.3% |
6.2% |
10.4% |
9.9% |
|
|
2-Jan-26 |
6.1% |
8.8% |
7.2% |
7.8% |
7.1% |
|
|
2-Nov-26 |
7.3% |
9.9% |
8.7% |
9.2% |
7.9% |
|
|
5-Nov-26 |
7.1% |
9.7% |
8.6% |
9.0% |
7.7% |
|
|
9-Nov-26 |
7.1% |
9.3% |
8.3% |
8.6% |
7.5% |
|
|
10-Nov-26 |
7.2% |
9.4% |
8.4% |
8.7% |
7.6% |
|
|
11-Nov-26 |
7.2% |
9.4% |
8.4% |
8.7% |
7.6% |
|
|
12-Nov-26 |
7.2% |
9.6% |
8.5% |
8.9% |
7.7% |
|
|
Weekly Change |
0.1% |
(0.1%) |
(0.1%) |
(0.1%) |
0.0% |
|
|
MTD Change |
(0.0%) |
(0.3%) |
(0.2%) |
(0.4%) |
(0.2%) |
|
|
YTD Change |
1.2% |
0.7% |
1.4% |
1.1% |
0.6% |
|
Source: Central Bank of Kenya (CBK)
Kenya Shilling:
During the week, the Kenya Shilling depreciated by 3.8 bps against the US Dollar, to Kshs 130.0 from the Kshs 129.9 recorded the previous week. On a year-to-date basis, the shilling has depreciated by 70.5 bps against the dollar, as compared to the 22.9 bps appreciation recorded in 2025.
We expect the shilling to be supported by:
-
Diaspora remittances decreased marginally by 1.1% to a cumulative USD 5,023.2 mn in the twelve months to October 2026, lower than the USD 5,081.6 mn recorded over the same period in 2025. These have continued to cushion the shilling against further depreciation. In the October 2026 diaspora remittances figures, North America remained the largest source of remittances to Kenya accounting for 45.4% in the period,
-
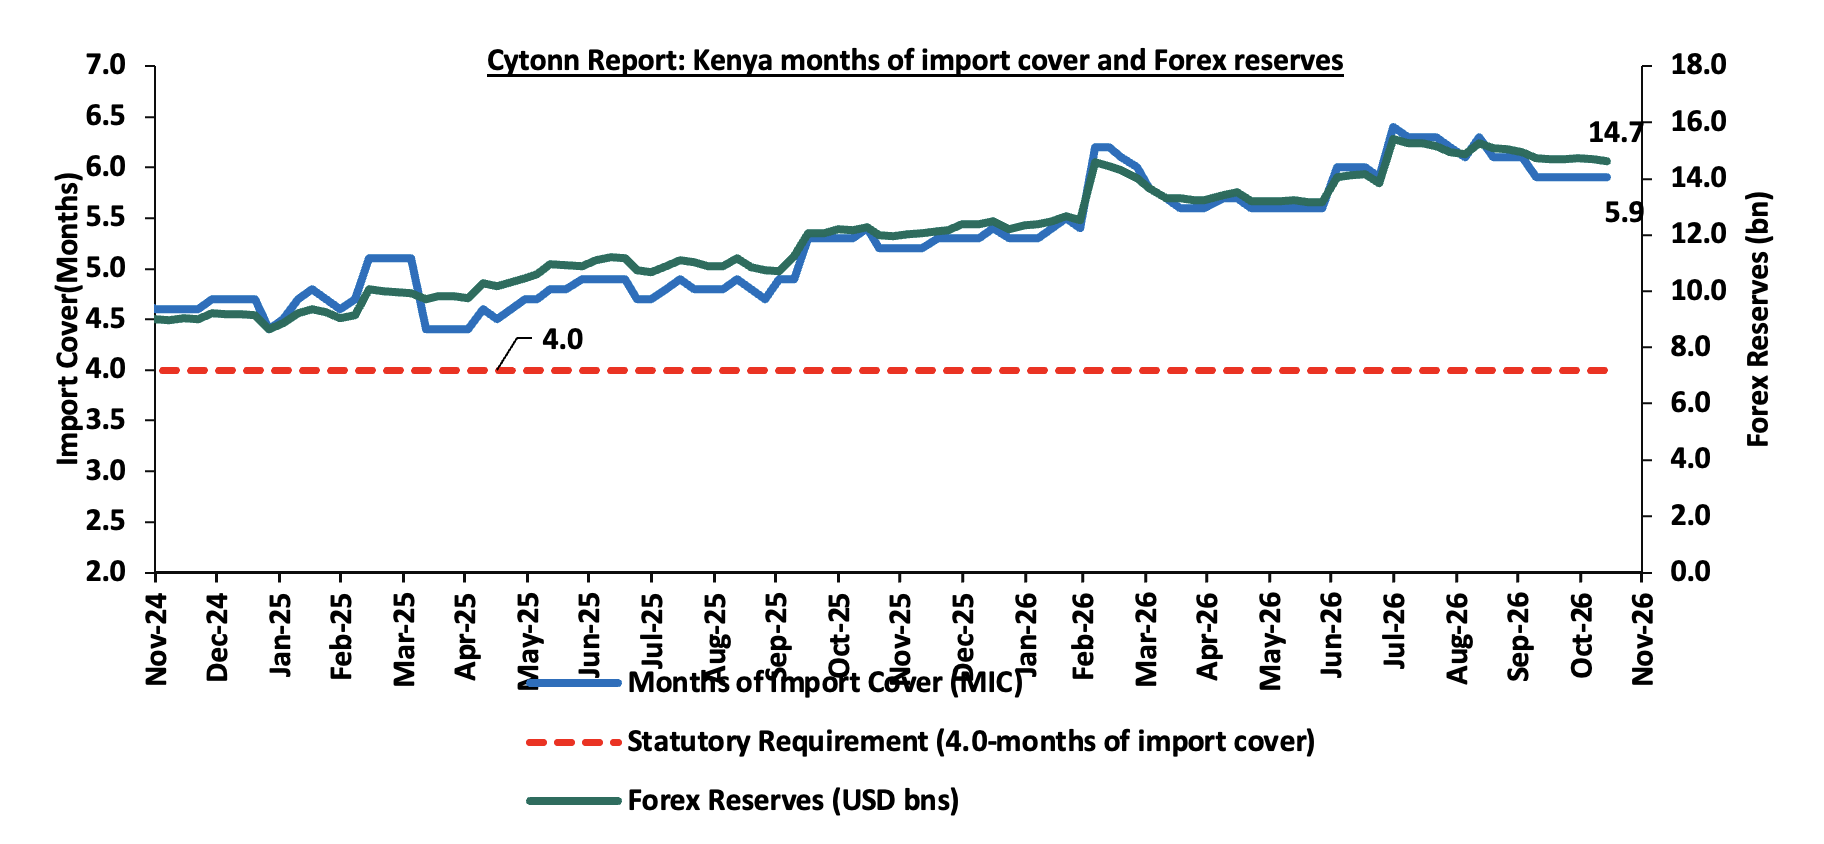
Improved forex reserves currently at USD 14.6 bn (equivalent to 5.9-months of import cover), which is above the statutory requirement of maintaining at least 4.0-months of import cover and above the EAC region’s convergence criteria of 4.5-months of import cover
The shilling is however expected to remain under pressure in 2026 as a result of:
-
An ever-present current account deficit which widened to 3.1% of GDP in the 12 months to August 2026 compared to 2.1% of GDP in a similar period in 2025 and,
-
The need for government debt servicing, continues to put pressure on forex reserves given that 54.5% of Kenya’s external debt is US Dollar-denominated as of August 2026.
-
Rising geopolitical tensions in the Middle East, which could exert pressure on the shilling through higher global oil prices and increased uncertainty in international markets. Given that Kenya is a net importer of petroleum products, any sustained increase in oil prices would widen the import bill, increase demand for US Dollars, and consequently put depreciation pressure on the shilling
Kenya’s forex reserves marginally decreased by 0.6% during the week to USD 14.6 bn from USD 14.7 bn recorded the previous week, equivalent to 5.9 months of import cover, and above the statutory requirement maintaining at least 4.0-months of import cover.
Weekly Highlights
-
Fuel Prices effective 15th November 2026 to 14th December 2026
During the week, the Energy and Petroleum Regulatory Authority (EPRA) released their monthly statement on the maximum retail fuel prices in Kenya, effective from 15th November 2026 to 14th December 2026. Notably, the maximum allowed prices for Kerosene, Super Petrol and Diesel remained unchanged at Kshs 219.9, Kshs 227.0 and Kshs 227.8 per litre, respectively, as the Government applied Kshs 4.6 bn from the Petroleum Development Levy Fund to stabilize prices.
Other key take-outs from the performance include,
-
The average landed cost of imported Super Petrol, Diesel and Kerosene increased by 6.1%, 6.7% and 0.7% to USD 1,037.3, USD 1,137.1 and USD 1,106.1 per cubic metre, respectively, in October 2026, from USD 977.6, USD 1,065.4 and USD 1,098.3 in September 2026.
-
The Kenyan Shilling depreciated marginally against the US Dollar by 20.0 bps to Kshs 130.17 in October 2026 from Kshs 129.91 in September 2026.
-
The prices are inclusive of Value Added Tax (VAT) at 8.0%, in line with Government policy to cushion consumers from the negative effects of high international prices. The Government also applied Kshs 4.6 bn from the Petroleum Development Levy Fund to stabilize the computed pump prices, cushioning consumers from increases of Kshs 8.58, Kshs 10.54 and Kshs 1.16 per litre on Super Petrol, Diesel and Kerosene, respectively.
-
International petroleum prices were mixed in October 2026. Super Petrol and Diesel prices decreased by 8.7% and 6.1% to USD 1,187.1 and USD 1,142.2 per metric tonne, respectively, from USD 1,300.7 and USD 1,215.8 in September 2026, while Kerosene prices increased marginally by 0.1% to USD 1,255.3 from USD 1,253.5.
Going forward, the outlook for fuel prices remains subject to developments in international petroleum prices, imported petroleum costs and the USD/Kshs exchange rate. Landed costs of Super Petrol and Diesel rose by 6.1% and 6.7% in October 2026, and without the Kshs 4.6 bn from the Petroleum Development Levy Fund, pump prices of Super Petrol and Diesel would have risen by Kshs 8.58 and Kshs 10.54 per litre. Continued reliance on the Fund to hold prices steady is therefore a key factor, and geopolitical tensions, particularly the US/Israel-Iran war and its impact on the Strait of Hormuz, could keep international prices and landed costs elevated. The relatively stable exchange rate limits currency movements as a source of pressure on local pump prices. Kenya imports its petroleum in refined form, so international prices and the exchange rate feed directly into local pump prices.
Rates in the fixed income market have declined MTD, reversing the recent upward trend. The decline comes despite the CBK's decision to pause its rate-cutting cycle at 8.75%, with inflation remaining elevated at 7.3%, just 0.2% points below the upper bound of CBK’s target range of 2.5%-7.5%. The government is 211.0% ahead of its prorated net domestic borrowing target of Kshs 919.4 bn, having a net borrowing position of Kshs 735.6 bn (inclusive of T-bills). We expect investors to maintain a preference for short to medium-term papers as they monitor the pace of government issuance and the path of inflation before committing further out on the curve, with the yield curve likely to remain under upward pressure rather than stabilize, at least until the inflation trajectory becomes clearer.
Market Performance:
During the week, the equities market was on an upward trajectory, with the NSE 10, NSE 25, NASI, and NSE 20 increasing by 1.7%, 1.3%, 0.8%, and 0.03% respectively, taking their YTD performance to gains of 35.2%, 33.4%, 33.2%, and 29.0% for NSE 10, NSE 20, NSE 25 and NASI respectively. The week-on-week equities market performance was mainly driven by gains recorded by large-cap stocks such as Co-operative, Absa, and Stanbic of 7.9%, 3.7%, and 2.3% respectively. The performance was however weighed down by losses recorded by large-cap stocks such as BAT, NCBA, and KCB of 2.0%, 0.8%, and 0.6% respectively.
During the week, the banking sector index increased by 1.5% to 284.1 from the 279.8 recorded the previous week. This is attributable to gains recorded by large cap stocks such as Co-operative, Absa, and Stanbic of 7.9%, 3.7%, and 2.3% respectively. The performance was however weighed down by losses recorded by large-cap stocks such as NCBA, KCB and DTBK of 0.8%, 0.6% and 0.4% respectively.
During the week, equities turnover decreased by 96.3% to USD 31.0 mn from USD 846.7 mn recorded the previous week, taking the YTD total turnover to USD 4,348.3 mn. Foreign investors became net sellers for the first time in two weeks with a net selling position of USD 2.4 mn, from a net buying position of USD 820.2 mn recorded the previous week, taking the YTD foreign net buying position to USD 620.3 mn, compared to a net selling position of USD 92.9 mn recorded in 2025.
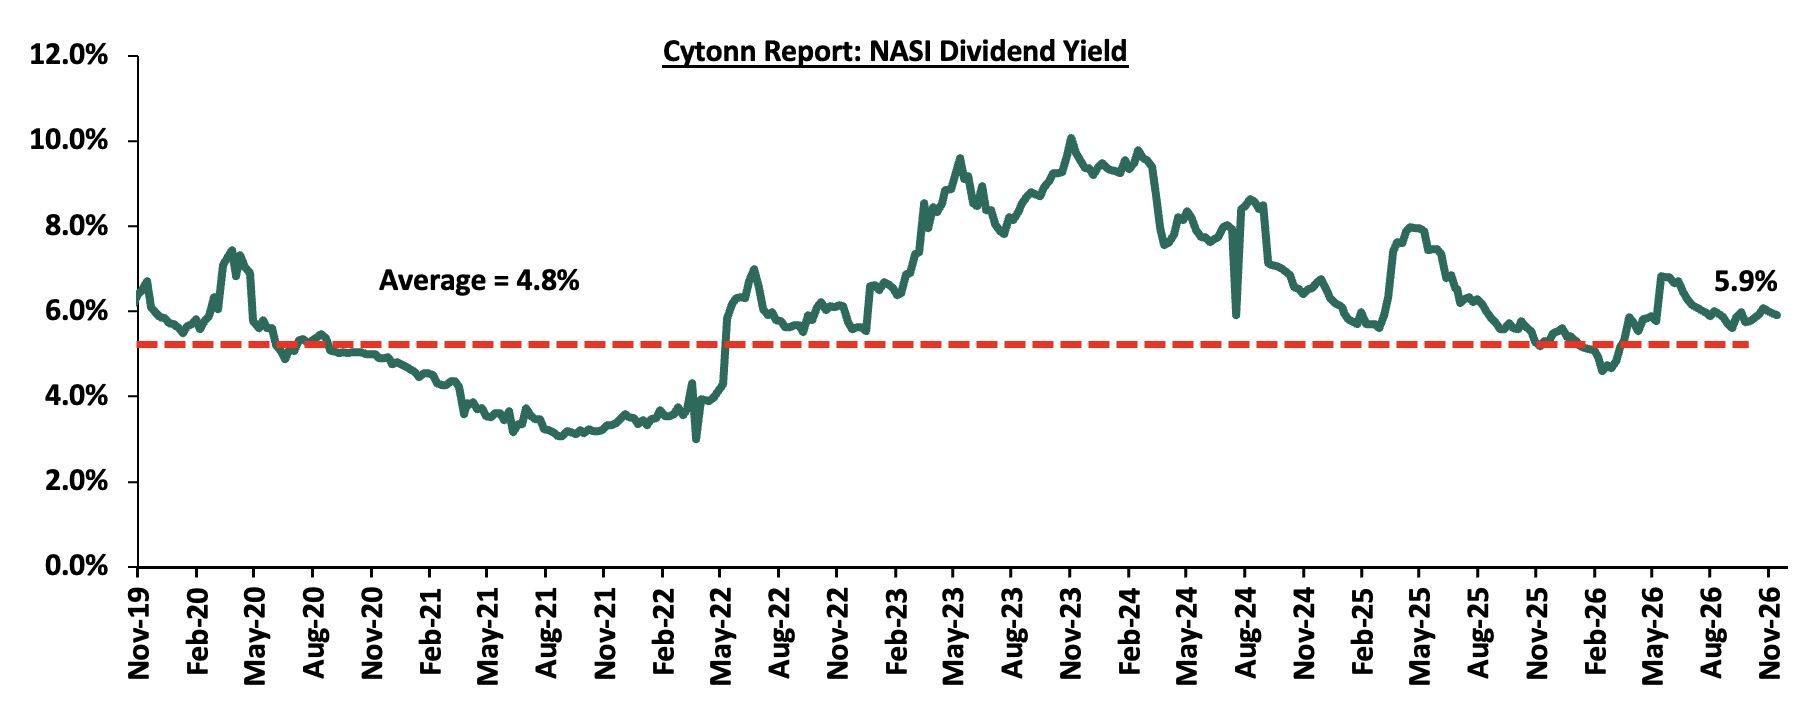
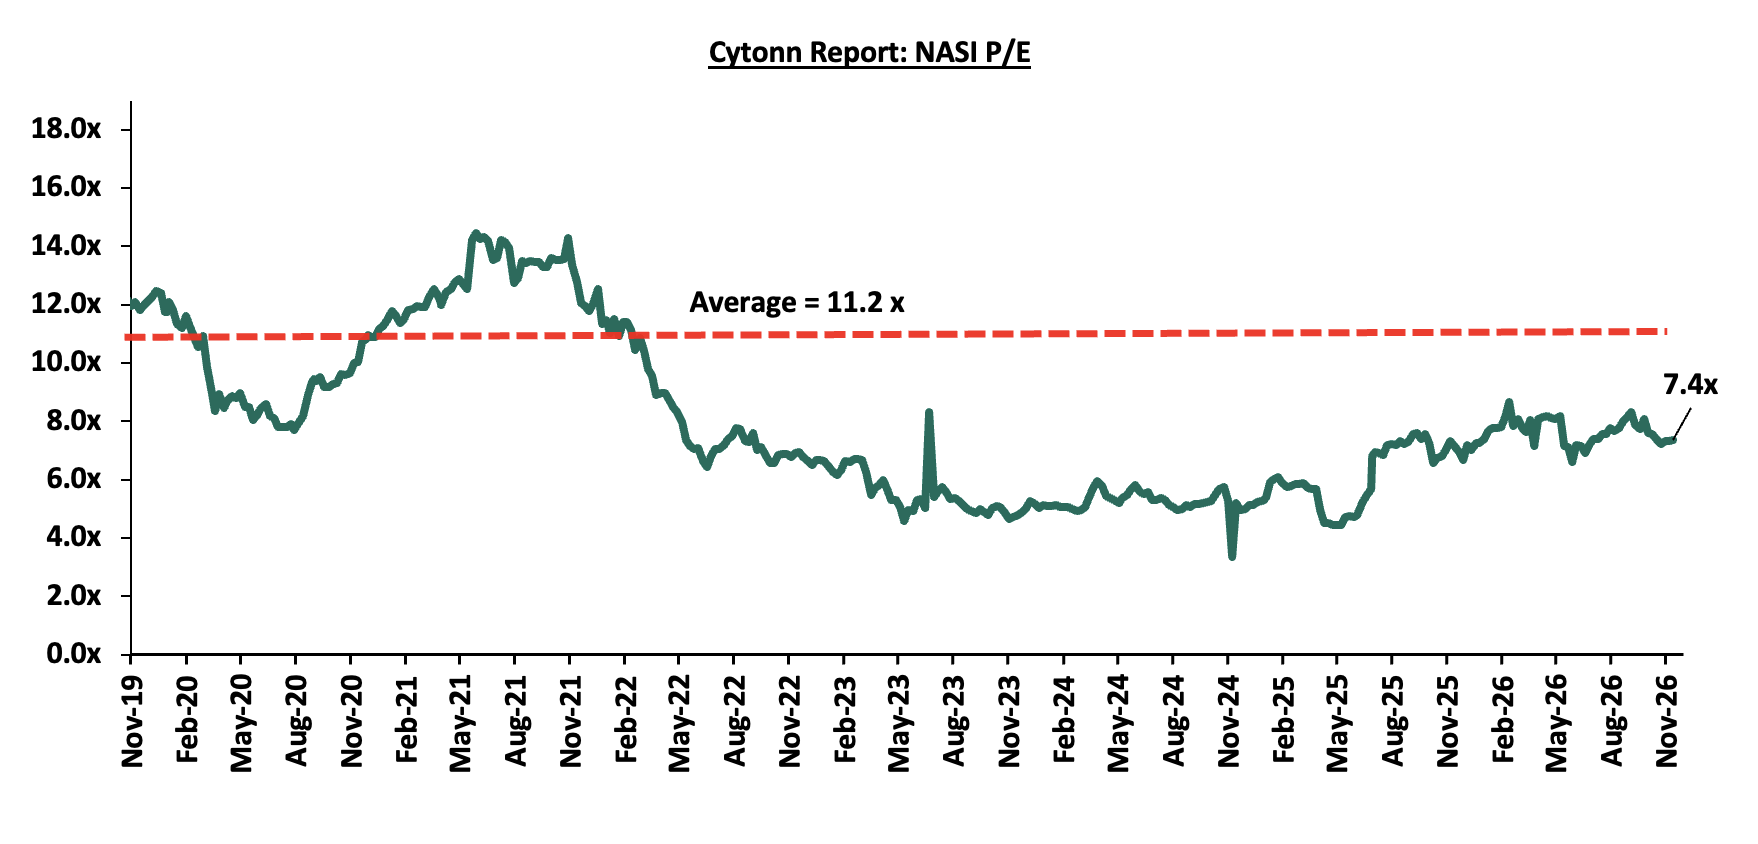
The market is currently trading at a price to earnings ratio (P/E) of 7.4x, 33.9% below the historical average of 11.2x, and a dividend yield of 5.9%, 1.2% points above the historical average of 4.8%. Key to note, NASI’s PEG ratio currently stands at 0.9x, an indication that the market is slightly undervalued relative to its future growth. A PEG ratio greater than 1.0x indicates the market may be overvalued while a PEG ratio less than 1.0x indicates that the market is undervalued;
During the week, Co-op Bank released their Q3’2026 financial results, recording a 27.2% increase in profit after tax to Kshs 27.4 bn in Q3’2026, from Kshs 21.6 bn in Q3’2025;
The charts below indicate the historical P/E and dividend yields of the market:
Universe of Coverage:
|
Cytonn Report: Equities Universe of Coverage |
|||||||||||
|
Price as at 06/11/2026 |
Price as at 13/11/2026 |
w/w change |
m/m change |
YTD Change |
Year Open 2026 |
Target Price* |
Dividend Yield |
Upside/ Downside** |
P/TBv Multiple |
Recommendation |
|
|
NCBA |
89.5 |
88.8 |
(0.8%) |
0.9% |
4.4% |
85.0 |
108.9 |
8.0% |
30.8% |
1.2x |
Buy |
|
KCB Group |
89.5 |
89.0 |
(0.6%) |
3.5% |
35.4% |
65.8 |
104.4 |
7.9% |
25.2% |
0.9x |
Buy |
|
Co-op Bank |
36.1 |
39.0 |
7.9% |
9.7% |
63.0% |
23.9 |
46.1 |
6.4% |
24.8% |
1.4x |
Buy |
|
Standard Chartered Bank |
303.3 |
308.8 |
1.8% |
1.3% |
3.0% |
299.8 |
345.8 |
10.0% |
22.0% |
1.9x |
Buy |
|
ABSA Bank |
30.9 |
32.0 |
3.7% |
6.8% |
28.8% |
24.9 |
36.8 |
6.4% |
21.5% |
1.8x |
Buy |
|
Equity Group |
99.0 |
100.0 |
1.0% |
5.3% |
49.3% |
67.0 |
113.5 |
5.8% |
19.3% |
1.3x |
Accumulate |
|
Stanbic Holdings |
266.3 |
272.3 |
2.3% |
4.9% |
37.7% |
197.8 |
300.3 |
8.2% |
18.5% |
1.5x |
Accumulate |
|
CIC Group |
4.9 |
4.6 |
(7.1%) |
(3.6%) |
0.7% |
4.5 |
5.1 |
2.8% |
13.6% |
1.2x |
Accumulate |
|
I&M Group |
85.0 |
83.5 |
(1.8%) |
2.8% |
95.1% |
42.8 |
90.4 |
4.5% |
12.8% |
1.3x |
Accumulate |
|
Family Bank |
26.7 |
27.3 |
2.1% |
0.4% |
51.4% |
18.0 |
29.5 |
4.4% |
12.7% |
1.4x |
Accumulate |
|
Diamond Trust Bank |
189.0 |
188.3 |
(0.4%) |
5.0% |
64.1% |
114.8 |
199.5 |
4.8% |
10.8% |
0.5x |
Accumulate |
|
Jubilee Holdings |
404.5 |
405.5 |
0.2% |
2.2% |
25.7% |
322.5 |
420.5 |
3.7% |
7.4% |
0.6x |
Hold |
|
Britam |
18.0 |
18.1 |
0.6% |
0.0% |
99.2% |
9.1 |
18.5 |
0.0% |
2.2% |
1.3x |
Lighten |
|
*Target Price as per Cytonn Analyst estimates **Upside/ (Downside) is adjusted for Dividend Yield ***Dividend Yield is calculated using FY’2025 Dividends |
|||||||||||
Weekly Highlights
-
Co-op Bank Q3’2026 Financial Performance
During the week, Co-op Bank released their Q3’2026 financial results, recording a 27.2% increase in profit after tax to Kshs 27.4 bn in Q3’2026, from Kshs 21.6 bn in Q3’2025;
|
Balance Sheet Items |
Q3'2025 |
Q3'2026 |
y/y change |
|
Government Securities |
255.4 |
271.1 |
6.1% |
|
Net Loans and Advances |
406.5 |
496.9 |
22.2% |
|
Total Assets |
815.3 |
907.4 |
11.3% |
|
Customer Deposits |
548.6 |
633.0 |
15.4% |
|
Deposits per branch |
2.5 |
2.8 |
11.8% |
|
Total Liabilities |
650.7 |
728.2 |
11.9% |
|
Shareholders’ Funds |
164.2 |
179.3 |
9.2% |
|
Balance Sheet Ratios |
Q3'2025 |
Q3'2026 |
y/y change |
|
Loan to Deposit Ratio |
74.1% |
78.5% |
4.4% |
|
Government Securities to Deposits Ratio |
46.6% |
42.8% |
(3.7%) |
|
Return on average equity |
18.8% |
20.7% |
1.9% |
|
Return on average assets |
3.6% |
4.1% |
0.6% |
|
Annualized dividend yield |
10.0% |
7.7% |
(2.3%) |
|
Income Statement |
Q3'2025 |
Q3'2026 |
y/y change |
|
Net Interest Income |
45.3 |
51.0 |
12.7% |
|
Non-Interest Income |
22.1 |
24.1 |
9.2% |
|
Total Operating income |
67.4 |
75.2 |
11.6% |
|
Loan Loss provision |
(7.4) |
(4.8) |
(34.2%) |
|
Total Operating expenses |
(37.7) |
(39.7) |
5.3% |
|
Profit before tax |
30.0 |
35.9 |
19.6% |
|
Profit after tax |
21.6 |
27.4 |
27.2% |
|
Core EPS |
3.7 |
4.7 |
27.2% |
|
Dividend Payout Ratio |
27.2% |
32.1% |
4.9% |
|
Annualized Dividend Yield |
10.0% |
7.7% |
(2.3%) |
|
Income Statement Ratios |
Q3'2025 |
Q3'2026 |
Y/Y Change |
|
Yield from interest-earning assets |
13.4% |
12.8% |
(0.6%) |
|
Cost of funding |
5.4% |
4.4% |
(1.0%) |
|
Net Interest Spread |
8.0% |
8.3% |
0.3% |
|
Net Interest Income as % of operating income |
67.2% |
67.9% |
0.7% |
|
Non-Funded Income as a % of operating income |
32.8% |
32.1% |
(0.7%) |
|
Cost to Income |
56.0% |
52.8% |
(3.1%) |
|
CIR without provisions |
45.1% |
46.4% |
1.3% |
|
Cost to Assets |
3.7% |
3.8% |
0.1% |
|
Net Interest Margin |
8.7% |
8.9% |
0.3% |
|
Capital Adequacy Ratios |
Q3'2025 |
Q3'2026 |
% points change |
|
Core Capital/Total deposit Liabilities |
24.3% |
22.2% |
(2.1%) |
|
Minimum Statutory ratio |
8.0% |
8.0% |
|
|
Excess |
16.3% |
14.2% |
(2.1%) |
|
Core Capital/Total Risk Weighted Assets |
20.3% |
20.0% |
(0.3%) |
|
Minimum Statutory ratio |
10.5% |
10.5% |
|
|
Excess |
9.8% |
9.5% |
(0.3%) |
|
Total Capital/Total Risk Weighted Assets |
22.7% |
21.3% |
(1.4%) |
|
Minimum Statutory ratio |
14.5% |
14.5% |
|
|
Excess |
8.2% |
6.8% |
(1.4%) |
|
Liquidity Ratio |
61.0% |
54.8% |
(6.2%) |
|
Minimum Statutory ratio |
20.0% |
20.0% |
|
|
Excess |
41.0% |
34.8% |
(6.2%) |
Key Take-Outs:
-
Increased earnings - Core earnings per share grew by 27.2% to Kshs 4.7, from Kshs 3.7 in Q3’2025, driven by the 11.6% increase in total operating income to Kshs 75.2 bn, from Kshs 67.4 bn in Q3’2025. However, the performance was weighed down by a 5.3% increase in total operating expenses to Kshs 39.7 bn from Kshs 37.7 bn in Q3’2025,
-
Improved asset quality - The bank’s Asset Quality improved, with the Gross NPL ratio declining by 4.2% points to 13.1% in Q3’2026, from 17.3% in Q3’2025, attributable to a 9.2% decrease in Gross non-performing loans to Kshs 71.7 bn, from Kshs 78.9 bn in Q3’2025, coupled with a 19.9% increase in gross loans to Kshs 547.7 bn, from Kshs 456.8 bn recorded in Q3’2025,
-
Expanded balance sheet - The balance sheet recorded an expansion as total assets increased by 11.3% to Kshs 907.4 bn, from Kshs 815.3 bn in Q3’2025, mainly driven by a 22.2% increase in net loans and advances to Kshs 496.9 bn from Kshs 406.5 bn and a 6.1% increase in government securities to Kshs 271.1 bn from Kshs 255.4 bn in Q3’2025.
For a more detailed analysis, please see our Co-op Bank Q3’2026 Earnings Note.
We maintain a “cautiously optimistic” short-term outlook supported primarily by earnings-led, attractive valuations, despite heightened geopolitical risks such as Iran war that may weigh on investor sentiment, and, “neutral” in the long term as persistent foreign investor outflows continue to constrain market liquidity and limit broad-based market re-rating. With the market currently trading at a discount to its future growth (PEG Ratio at 0.9x), where performance will be driven by company-specific fundamentals rather than general market direction, we believe that investors should reposition towards value stocks exhibiting strong earnings growth, attractive dividend yields, solid balance sheets, sustainable competitive advantages and trading at compelling discounts to their intrinsic value. While foreign investor sell-offs are expected to continue exerting pressure in the near term, we believe this will create selective entry opportunities for long-term investors
-
Industry Report
-
Hass Consult Q3’2026 Land Index
During the week, Hass Consult, a Kenyan consulting and Real Estate development firm, released its Land Price Index Q3'2026 Report, highlighting the performance of the Real Estate land sector in the Nairobi Metropolitan Area (NMA). The following are the key take-outs from the report:
-
Land prices in Nairobi’s suburbs slowed, growing by 0.7% q/q in Q3'2026, 0.7% points lower than the 1.4% recorded in Q2'2026 and the slowest quarterly growth in three years, while land prices in the satellite towns similarly slowed, growing by 0.7% q/q, down from 1.4% in the previous quarter. On an annual basis, the Nairobi Suburbs-18 Composite Index posted a 4.3% gain, while the Nairobi Satellite-14 Composite Index also recorded 4.3% growth, with the two indices having grown 1.3-fold and 1.8-fold, respectively, since 2016. The slowdown can be attributed to a shift in demand towards completed houses, as lower borrowing costs and constrained supply in established suburbs lifted suburban house prices by 2.3% q/q, the strongest in four years and well ahead of the 0.7% q/q growth in land prices, while in the satellite towns, affordability pressures, with house prices declining for a second consecutive quarter, continued to weigh on demand.
-
In the Nairobi suburbs, 13 of the 18 surveyed suburbs recorded positive price growth, led by Karen at 3.0% q/q to Kshs 81.8 mn per acre, followed by Westlands at 2.7% q/q to Kshs 521.7 mn and Kitisuru at 2.6% q/q to Kshs 105.2 mn per acre. Several of the Q2'2026 leaders slowed sharply, with Langata easing to 0.2% q/q from 4.1% to Kshs 94.9 mn per acre, while five suburbs recorded price declines, led by Muthangari at (3.1%), Gigiri at (2.2%) and Riverside at (1.5%). On an annual basis, Karen posted the strongest gain at 10.9% and has recorded cumulative appreciation of about 19.6% over the past eight quarters, the highest among the 18 suburbs, while Muthangari recorded the weakest performance both on a quarterly and annual basis, at (3.1%) and (8.6%), respectively.
-
In the satellite towns, nine of the 14 towns recorded positive price growth, up from seven in Q2'2026, led by Ngong at 2.2% q/q to Kshs 35.5 mn per acre, Thika at 2.0% q/q to Kshs 33.0 mn and Ruaka at 1.9% q/q to Kshs 117.9 mn per acre. Ngong and Limuru, at 1.2% q/q to Kshs 27.5 mn per acre, returned to positive growth after declines in Q2'2026, while Ruiru, Thika and Ruaka slowed from the 4.1%, 3.8% and 2.8% q/q recorded in the previous quarter. The five towns that recorded declines were led by Mlolongo at (2.2%) and Kiserian at (2.0%), followed by Kiambu at (1.0%), Ongata Rongai at (0.9%) and Tigoni at (0.1%). On an annual basis, Ruiru posted the strongest gain at 11.5%, while Athi River recorded the weakest performance at (2.3%).
The moderation in land price growth is also reflected in our Cytonn Q3'2026 Markets Review, in which the overall land sector in the Nairobi Metropolitan Area (NMA) recorded an annual price appreciation of 1.3% in Q3'2026, lower than the 4.3% annual gains posted by the Hass Consult composite indices. In our review, commercial areas in the Nairobi suburbs led with an appreciation of 2.5%, while high-rise residential areas recorded the least movement at 0.3%, and serviced and unserviced land in the satellite towns appreciated by 2.3% and 0.9%, respectively.
-
Hass Consult Q3’2026 Property Index
During the week, Hass Consult, a Kenyan consulting and Real Estate development firm, published its House Price Index Q3'2026 Report, highlighting the performance of the Real Estate property sector in the Nairobi Metropolitan Area (NMA). The following are the key take-outs from the report;
-
Property prices in Nairobi's suburbs grew by 2.3% q/q in Q3'2026 to Kshs 33.9 mn, an acceleration from the 0.9% q/q growth recorded in Q2'2026 and the strongest quarterly growth in four years, with all 14 surveyed suburbs recording positive house price growth. Growth was led by Spring Valley at 6.8% q/q to Kshs 79.4 mn, Westlands at 5.9% q/q to Kshs 64.5 mn and Muthaiga at 5.5% q/q to Kshs 118.1 mn, followed by Karen and Loresho at 5.2% q/q each, to Kshs 119.3 mn and Kshs 86.0 mn, respectively. On an annual basis, the Nairobi Suburbs-18 Composite Sales Index recorded a 5.2% appreciation, having grown 2.14-fold since October 2016, with houses in Spring Valley posting the strongest annual gain at 16.4%. The stronger performance is mainly attributable to lower borrowing costs, with Central Bank of Kenya data showing average commercial bank lending rates at 14.4% in September 2026, 0.7% points lower than the 15.1% recorded in September 2025 and relatively unchanged from the 14.4% recorded in June 2026, while annual private-sector credit growth reached 10.6% in September 2026, up from 5.0% in September 2025, alongside constrained housing supply in established suburbs;
-
In contrast, satellite town property prices declined by 0.6% q/q to Kshs 14.4 mn from Kshs 14.5 mn in Q2'2026, the second consecutive quarterly decline, with five of the 10 surveyed towns recording falling house prices and four of the nine satellite apartment markets also posting price declines. The decline was led by Ngong at (1.2%) q/q to Kshs 19.1 mn, Ongata Rongai at (1.0%) q/q to Kshs 15.4 mn, Juja at (0.6%) q/q to Kshs 12.8 mn and Kitengela at (0.5%) q/q to Kshs 13.2 mn. On an annual basis, the Nairobi Satellite-14 Composite Sales Index recorded a 2.0% decline, having still grown 3.1-fold since October 2016, with houses in Ngong posting the weakest annual performance at (7.3%), reflecting the sensitivity of satellite towns to affordability and competing housing options;
-
On the rental front, rents in Nairobi's suburbs grew by 2.7% q/q, up from 1.4% in Q2'2026 and approaching a three-year high, led by Loresho at 6.2% q/q to an average monthly house rent of Kshs 338,100, Kitisuru at 5.1% q/q to Kshs 350,100, Muthaiga at 4.5% q/q to Kshs 370,900 and Gigiri at 3.9% q/q to Kshs 402,100. The concentration of rental growth in established diplomatic and international neighbourhoods is partly attributable to the expansion of United Nations operations and the gradual relocation of personnel to Nairobi. Satellite town rents grew by a slower 0.4% q/q, from 1.1% in the previous quarter, with apartments in Ruaka recording the weakest annual performance at (7.2%). On an annual basis, suburb and satellite rents grew by 7.1% and 4.1%, respectively, having grown 2.29-fold and 3.17-fold since October 2016.
The Q3'2026 data points to a growing divergence within the residential market. While house prices in established suburbs rallied, apartment prices were mixed, with Parklands at (2.4%), Westlands at (2.2%) and Riverside at (1.3%) recording q/q declines, and satellite towns continued to lag. This is consistent with our Cytonn Q3'2026 Markets Review, in which average total returns to detached-unit investors improved by 2.2% points y/y to 7.7%, while those to apartment investors rose by only 0.2% points to 8.4%, with lower apartment rental yields largely offset by capital appreciation. This suggests that the recovery is being led by capital gains in the detached housing segment of the established suburbs, while apartments and satellite towns lag.
-
Hospitality Sector
-
Kenya Airways Slips to Sixth in Africa’s Airline Traffic Rankings
During the week, Kenya Airways (KQ) was ranked sixth in Africa by traffic, by Cirium, a global aviation analytics firm as capacity constraints in 2025 and most of 2026 cut its passenger numbers and reduced its share of the African aviation market. KQ’s revenue passenger kilometres (RPKs), a measure of travellers carried by number of kilometres flown, declined by 18.2% to 9,982 mn in 2025 from 12,204 mn in 2024, while its available seat kilometres (ASKs), a measure of available seats on aircraft times kilometres flown, fell by 17.7% to 13,349 mn from 16,227 mn. KQ’s global ranking consequently slipped to 107th from 96th, behind Air Algerie, whose RPKs rose by 17.0% to 12,174 mn (100th globally) on a 16.0% increase in capacity, and South African budget airline FlySafair, whose RPKs rose by 9.0% to 10,199 mn (104th globally). Ethiopian Airlines remained the dominant player on the continent, with RPKs rising by 18.0% to 70,071 mn as it expanded capacity by 17.0%, and its global ranking improving to 34th from 36th, followed by EgyptAir at 26,999 mn and Royal Air Maroc at 20,110 mn, which also grew traffic by 17.0% and moved to 83rd globally from 86th.
The decline was supply-driven rather than demand-driven, as KQ’s load factor, measured as RPKs as a share of ASKs, was broadly flat at 74.8% in 2025 from 75.2% in 2024. The capacity contraction was attributable to a shortage of aircraft parts, which forced the carrier to operate significantly below optimum capacity, with at least three of its Boeing 787 Dreamliners grounded for maintenance, cutting available capacity by up to 20.0% last year. The constraints have also pushed the airline back into loss-making after returning to profit in 2024. As a result, KQ, which has traditionally benefited from an extensive long-haul inter-continental and cross-regional intra-Africa route network, is increasingly being outpaced by its African peers. This is a headwind for the hospitality sector, as constrained capacity on the national carrier limits inbound arrivals into Nairobi, which weighs on occupancy and room rates for hotels and serviced apartments, and on demand for commercial developments near JKIA.
Going forward, we expect the Kshs 45.4 bn government support announced in October to restore KQ’s grounded fleet to gradually rebuild the carrier’s capacity, supporting international arrivals into Nairobi and, in turn, occupancy and rates for hotels and serviced apartments, particularly in the upscale segment that relies on business and international guests, as well as demand for airport-adjacent developments near JKIA. However, we expect the recovery to be gradual, given that peers such as Ethiopian Airlines and Air Algerie expanded capacity by 17.0% and 16.0%, respectively, in 2025, and the sector to remain exposed to execution risk on the fleet restoration, aircraft parts supply constraints, and KQ’s financial position.
-
REITs Weekly Performance
On the Unquoted Securities Platform Acorn D-REIT and I-REIT traded at Kshs 29.7 and Kshs 24.4 per unit, respectively, as per the last updated data on 30th October 2026. The performance represented a 48.3% and 22.2% gain for the D-REIT and I-REIT, respectively, from the Kshs 20.0 inception price. The volumes traded during the week for the D-REIT and I-REIT came in at 49,228 and 425,844 units, respectively. Additionally, ILAM Fahari I-REIT closed at Kshs 13.8 per unit as of 30th October 2026, representing a 31.0% loss from the Kshs 20.0 inception price, with no trades recorded during the week. REITs offer various benefits, such as tax exemptions, diversified portfolios, and stable long-term profits. However, the mixed performance of Kenyan REITs, with ILAM Fahari I-REIT still trading below its inception price, and the restructuring of their business portfolios are hindering significant investments. Additional general challenges include:
-
Insufficient understanding of the investment instrument among investors leading to a slower uptake of REIT products,
-
Lengthy approval processes for REIT creation,
-
High minimum capital requirements of Kshs 100.0 mn for REIT trustees compared to Kshs 10.0 mn for pension funds Trustees, essentially limiting the licensed REIT Trustee to banks only
-
The rigidity of choice between either a D-REIT or an I-REIT forces managers to form two REITs, rather than having one Hybrid REIT that can allocate between development and income earning properties
-
Limiting the type of legal entity that can form a REIT to only a trust company, as opposed to allowing other entities such as partnerships, and companies,
-
REITs should be given time before they are required to list. They would be allowed to stay private for a few years first, given that not all companies may be comfortable with listing on day one, and,
-
Minimum subscription amounts or offer parcels set at Kshs 0.1 mn for D-REITs and Kshs 5.0 mn for restricted I-REITs. The significant capital requirements still make REITs relatively inaccessible to smaller retail investors compared to other investment vehicles like unit trusts or government bonds. Together, these challenges continue to limit the performance of Kenyan REITs.
We expect the performance of Kenya's Real Estate sector to remain resilient, supported by several factors, including: i) the continued price growth in Nairobi's suburbs property market, growing by 2.3% q/q in Q3’2026 per the Hass Consult Property Index Q3'2026 Report, ii) the 2.7% q/q growth in suburban rents, iii) the lower borrowing costs, with average commercial bank lending rates at 14.4% in September 2026, and iv) the positive land price growth recorded in 13 of the 18 Nairobi suburbs and nine of the 14 satellite towns. However, the sector’s optimal performance will continue to be constrained by several challenges, including: i) the second consecutive quarterly decline in satellite town property prices, ii) the slowdown in land price growth to 0.7% q/q in the suburbs, iii) elevated inflation at 7.3% alongside rising construction costs, which weigh on household purchasing power, and iv) weak investor appetite in listed REITs like ILAM Fahari I-REIT, alongside high capital requirements.
-
Circle and Global Citizen Partner to Expand USDC Payments and Digital Financial Inclusion Across Africa
During the week, Circle Internet Group announced a multi-year partnership with Global Citizen to expand digital financial access and economic opportunities across Africa, beginning with the Move Afrika initiative. Starting in Rwanda in 2027, the partnership will introduce USDC payments for participating vendors and suppliers, with the aim of reducing transaction costs, accelerating settlement and improving access to international commerce. Circle will also provide financial education and technical training to local businesses and production professionals, while the partners explore onchain charitable funding and digital rewards for civic participation. The partnership strengthens Circle’s USDC adoption strategy by extending its use into Africa’s creative economy and demonstrating its potential in real-world commercial payments beyond trading and crypto-native activities. Increased merchant adoption could support USDC circulation and reinforce Circle’s position in the stablecoin payments market, although the immediate financial impact is likely to be limited by the initiative’s initial geographic scope, with broader benefits dependent on merchant uptake, transaction volumes, regulatory conditions and expansion into additional African markets.
-
Global Payments Integrates Visa IDX API to Improve Payment Authorization and Reduce False Declines
During the week, Global Payments Inc. announced the expansion of its AI powered Adaptive Authentication platform through the integration of Visa Intelligent Data Exchange (IDX) API, initially supporting eligible domestic transactions in the United States and Canada. The enhancement enables merchants to share richer transaction data with issuers to improve authorization decisions, increase approval rates and reduce false declines and unnecessary customer authentication challenges. Global Payments indicated that previous deployments of its Data Only authentication and AI-powered optimization model had delivered typical approval-rate improvements of 4.0% to 6.0%. The integration strengthens Global Payments’ value-added services offering by combining AI-driven authentication with Visa’s transaction data capabilities and Ravelin’s fraud and risk solutions, potentially improving merchant sales conversion, payment volumes and client retention. However, the near-term impact will depend on adoption among eligible merchants and whether improved authorization rates translate into sustained revenue growth, particularly as Visa IDX API remains limited to domestic U.S. and Canadian transactions.
-
Digital Payments Stock Performance
The table below presents a snapshot of NYSE-listed digital payments stocks, covering Visa, Mastercard, American Express (AXP), Circle, Block, Global Payments and PayPal:
|
Cytonn Report: Digital Payments NYSE stock performance |
||||||
|
Company |
Year Open 2026 |
Price 06/11/2026 |
Price 13/11/2026 |
w/w change |
YTD change |
Forward P/E |
|
American Express |
372.7 |
321.0 |
319.4 |
(0.5%) |
(14.3%) |
|
|
Visa |
346.5 |
422.7 |
425.4 |
0.7% |
22.8% |
|
|
Mastercard |
563.1 |
652.7 |
660.5 |
1.2% |
17.3% |
|
|
Circle |
83.5 |
67.9 |
62.4 |
(8.1%) |
(25.3%) |
|
|
Block |
65.2 |
85.5 |
84.6 |
(1.0%) |
29.9% |
|
|
PayPal Holdings |
58.1 |
59.2 |
59.4 |
0.2% |
2.1% |
|
|
Global Payments Inc |
77.0 |
97.4 |
91.9 |
(5.6%) |
19.4% |
|
|
Average |
25.8x |
|||||
Source: Visa, AXP, Circle, Global Payments, Mastercard, Block and PayPal financials, NYSE, PE* calculated using forward estimates FY’2027 financials
The stocks are currently trading at an average forward P/E multiple of 25.8x, indicating that investors are pricing in strong future earnings growth and are prepared to pay a substantial premium for current earnings. This also suggests that valuations may be stretched relative to near-term fundamentals.
We expect the global digital payments sector to continue shifting toward greater payment sovereignty and reduced reliance on traditional card-based networks, as governments and financial institutions prioritize control over domestic payment ecosystems. The European Central Bank's progress toward launching the Digital Euro signals a growing move toward central bank-backed payment infrastructure, which is likely to intensify competition with established private networks such as Visa Inc. and Mastercard Incorporated. However, despite these favorable long-term tailwinds, valuations remain elevated, with the companies under coverage trading at an average forward P/E of 25.8x, suggesting that much of the expected growth may already be priced in. As such, we expect near-term performance to remain sensitive to regulatory developments, execution risk, and how quickly incumbents and new entrants adapt to the changing payments landscape.
Foreign Direct Investments (FDIs) refer to investments made by a firm or individual in one country into business interests located in another country. Generally, FDI takes place when an investor establishes foreign business operations or acquires foreign business assets, including establishing ownership or controlling interest in a foreign company. FDIs are crucial for economic growth as they not only bring investment capital but also facilitate technology transfer, management skills, and international trade integration, which can lead to higher productivity, employment, and economic stability in the host country.
Kenya’s FDI inflows increased by 37.7% to USD 3,200.0 mn in 2025 from USD 2,324.0 mn in 2024, the highest on record. Having long been described as lagging its peers, Kenya now faces a different question: whether it can keep this momentum. We analyze the historical trend, compare Kenya with peer and advanced economies, and set out actionable initiatives. We shall cover the following:
-
Overview of Foreign Direct Investments in Kenya,
-
Economic Benefits of FDIs and Challenges to FDI Growth in Kenya,
-
Recommendations, and,
-
Conclusion and our Outlook.
Section I: Overview of Foreign Direct Investments in Kenya
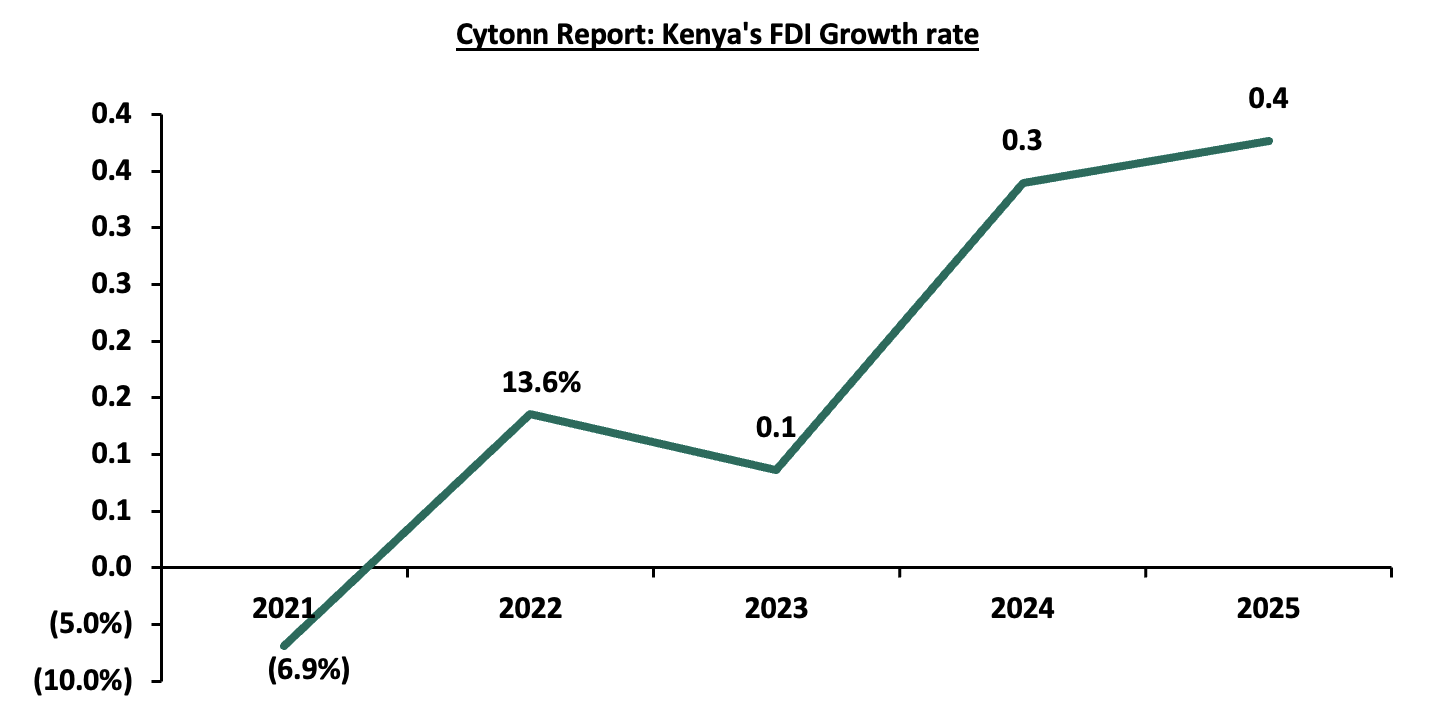
According to the United Nations Conference on Trade and Development (UNCTAD) World Investment Report 2026, global Foreign Direct Investments (FDIs) inflows increased by 6.0% in 2025 to USD 1.6 tn, from USD 1.5 tn in 2024. The increase was driven largely by swings in flows through major financial centers and investment hubs, and by stronger inflows in a limited number of large economies. Europe alone increased by USD 80.6 bn, 87.1% of the global increase. Excluding conduit flows through major European financial centers, global FDI rose 4.0%, after two consecutive years of decline. Underlying activity was weaker than the headline suggests. Cross-border M&A values fell 7.3% to USD 421.0 bn from USD 454.0 bn, and greenfield announcements stayed close to 2024 levels, supported mainly by megaprojects in data centers, oil and gas, and semiconductors. Against this backdrop, Kenya’s FDI inflows rose 37.7% to a record USD 3,200.0 mn in 2025, from USD 2,324.0 mn in 2024. The chart below shows Kenya’s FDI inflows growth rate over the past five years:
Source: UNCTAD
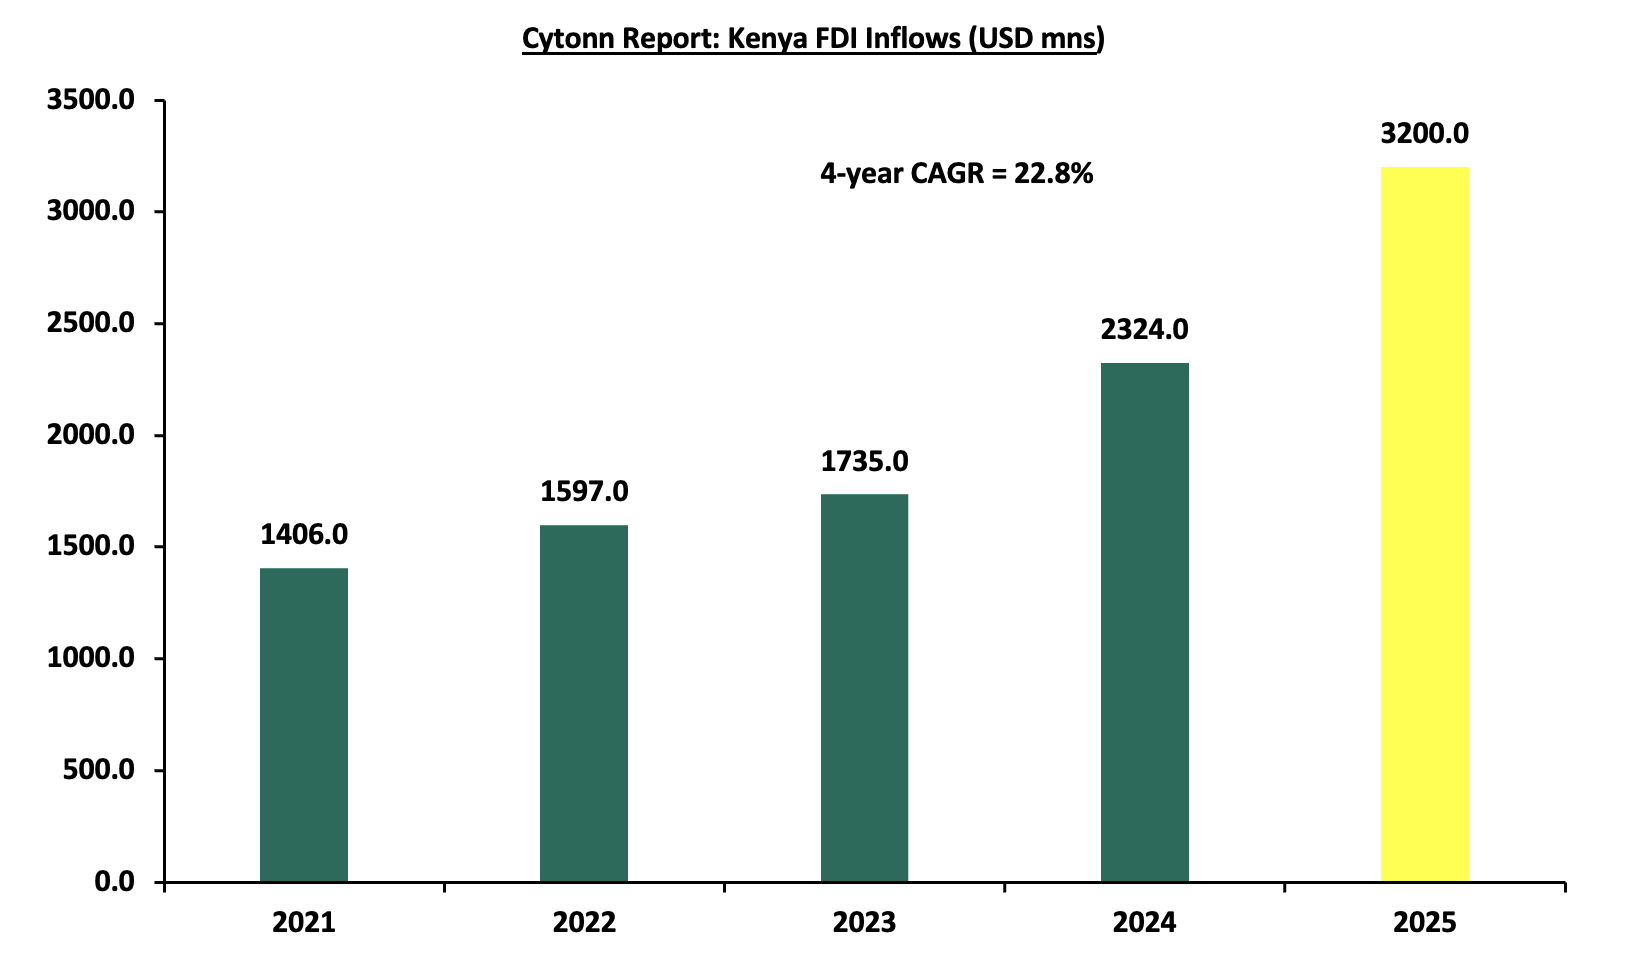
The improvement on the growth rate was mainly attributable to Kenya’s investment reforms and its renewable-powered digital infrastructure pipeline. FDIs into the country have increased over the years, recording a 4-year CAGR of 22.8% to USD 3,200.0 mn in 2025, from USD 1,406.0 mn in 2021. The chart below shows the movement in Kenya’s FDI inflows over the years;
Source: UNCTAD
An important caveat is that UNCTAD has revised Kenya’s history. In earlier editions, 2024 inflows were reported at USD 1,503.0 mn, a marginal decline of 0.1%. On the current series, 2024 was USD 2,324.0 mn, a 33.9% increase on 2023. The earlier picture of stagnation no longer holds. This is attributable to Kenya’s growing pull in digital infrastructure and clean energy as evidenced by a USD 1.0 bn investment package that includes a geothermal-powered data center. Kenya’s clean energy mix has been identified as a key factor in investor confidence, particularly among global technology firms seeking reliable, low-carbon power. This is consistent with UNCTAD’s wider finding that investment became more selective, concentrated in a limited number of host economies and in capital- and technology-intensive sectors. Kenya’s gains therefore depend on a small number of large projects, which makes year-to-year inflows lumpy.
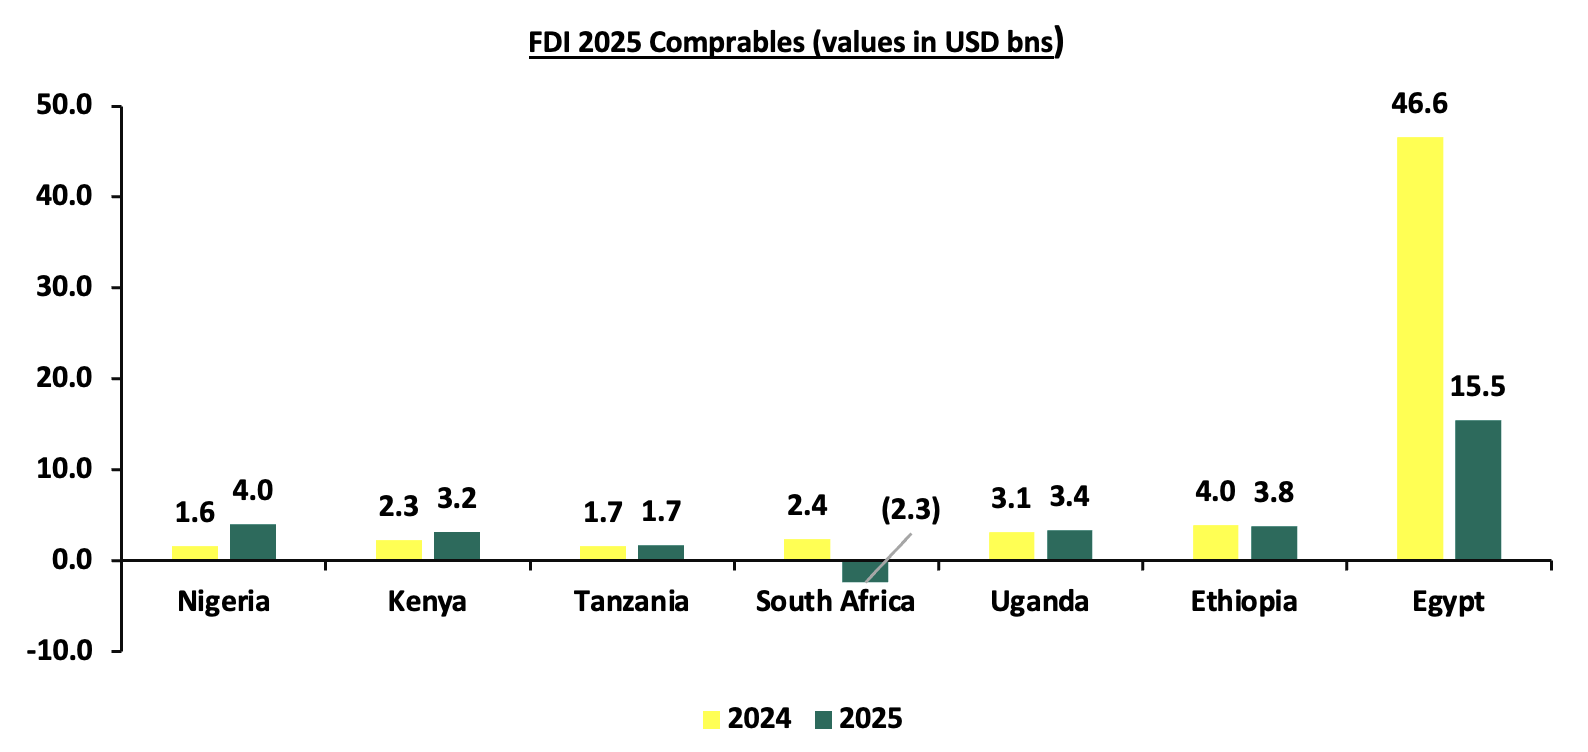
Africa moved against the global trend. Inflows fell 26.3% to USD 69.5 bn in 2025, from USD 94.3 bn in 2024. The fall largely reflects a high base. 2025 was still the third-highest year on record since 1990, and about a third above the continent’s long-term average. East Africa did better than the continent. Regional inflows rose 12.1% to USD 14.6 bn from USD 13.0 bn, and Kenya’s share rose to 21.9% from 17.8%. Kenya, Somalia, Burundi, Tanzania and Uganda recorded increases, while South Sudan and Ethiopia recorded declines. Kenya still ranks third in the region. Ethiopia received USD 3.8 bn, down 4.7% from USD 4.0 bn, and Uganda USD 3.36 bn, up 7.8% from USD 3.12 bn, while Tanzania received USD 1.72 bn, up 3.7% from USD 1.66 bn.
Egypt explains much of the continental swing. Its inflows fell 66.8% to USD 15.5 bn from USD 46.6 bn, after the 2024 surge driven by the Ras El-Hekma urban development project. The project is valued at an estimated USD 35.0 bn and sponsored by Abu Dhabi Developmental Holding in partnership with the Egyptian government. Egypt remained Africa’s largest recipient in 2025, with USD 15.5 bn. Nigeria moved the other way: inflows rose 148.1% to USD 4.0 bn from USD 1.6 bn, mainly attributable to oil and gas–related international project finance deals, including one project valued at USD 2.0 bn. This came despite net cross-border M&A divestments of USD 2.4 bn, including Shell’s sale of its onshore oil assets. The chart below compares FDI inflows in 2024 and 2025 in select economies:
Source: UNCTAD-World Investment Report 2026
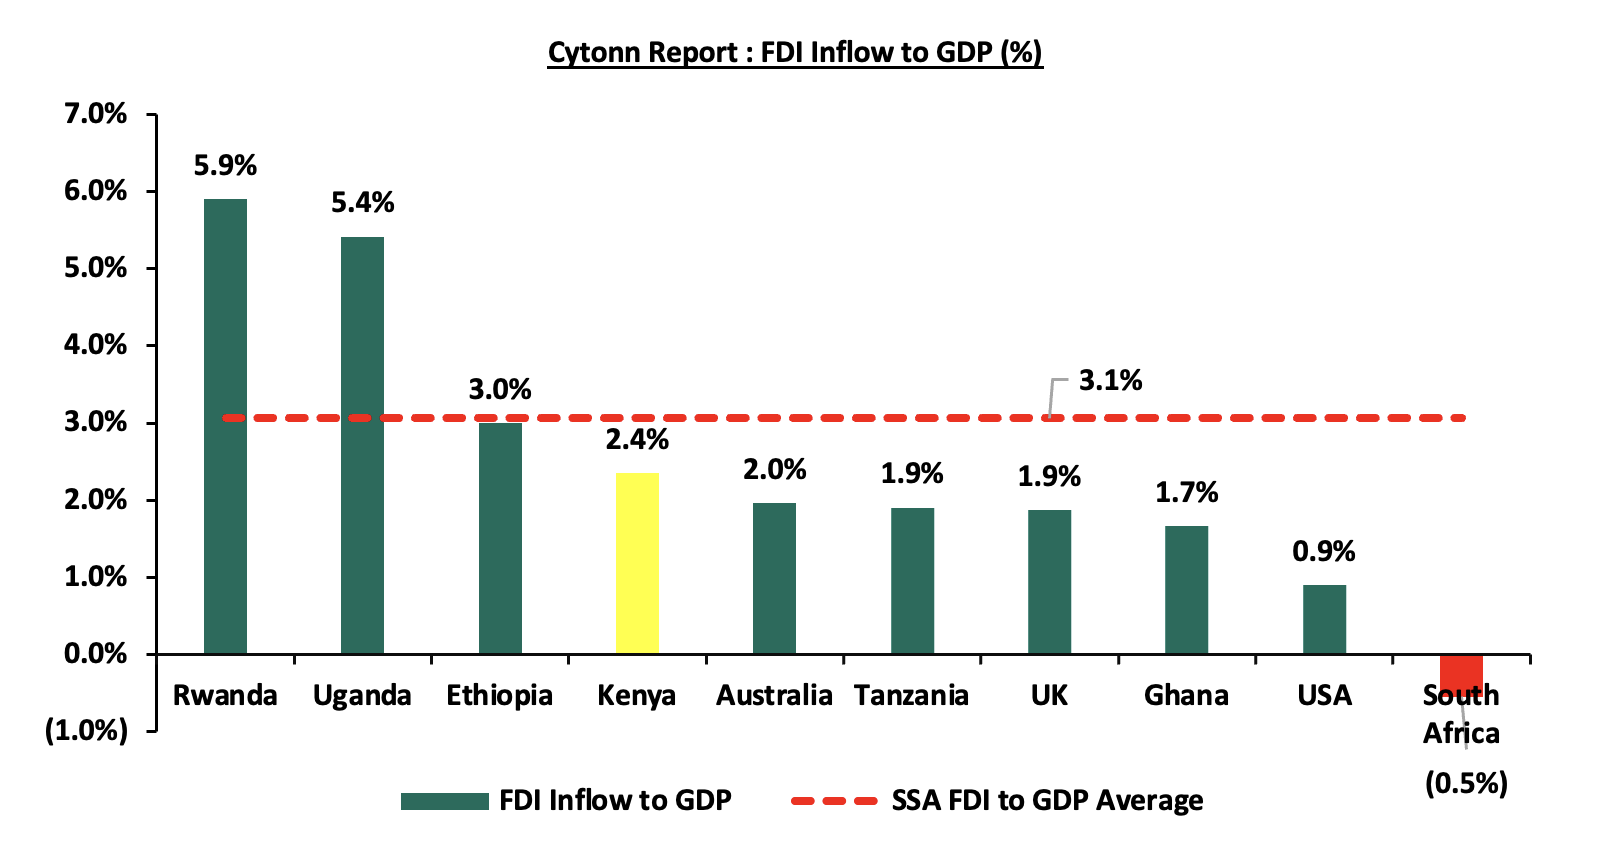
Kenya’s 2025 nominal GDP was Kshs 17.6 tn. At the 2025 average exchange rate of Kshs 129.30 to the dollar, that implies GDP of USD 135.9 bn, and FDI inflows of 2.4% of GDP. Wider economic growth was moderate, with real GDP growth easing to 4.6% in 2025 from 4.7% recorded in 2024. On this measure, Kenya’s FDI intensity was below the SSA average of 3.1%, and above the global average of 1.4%. The chart below compares Kenya’s FDI to GDP ratio with peer and advanced economies:
Source: World Bank, UNCTAD, data as of 2026
Sources of Foreign Direct Investments
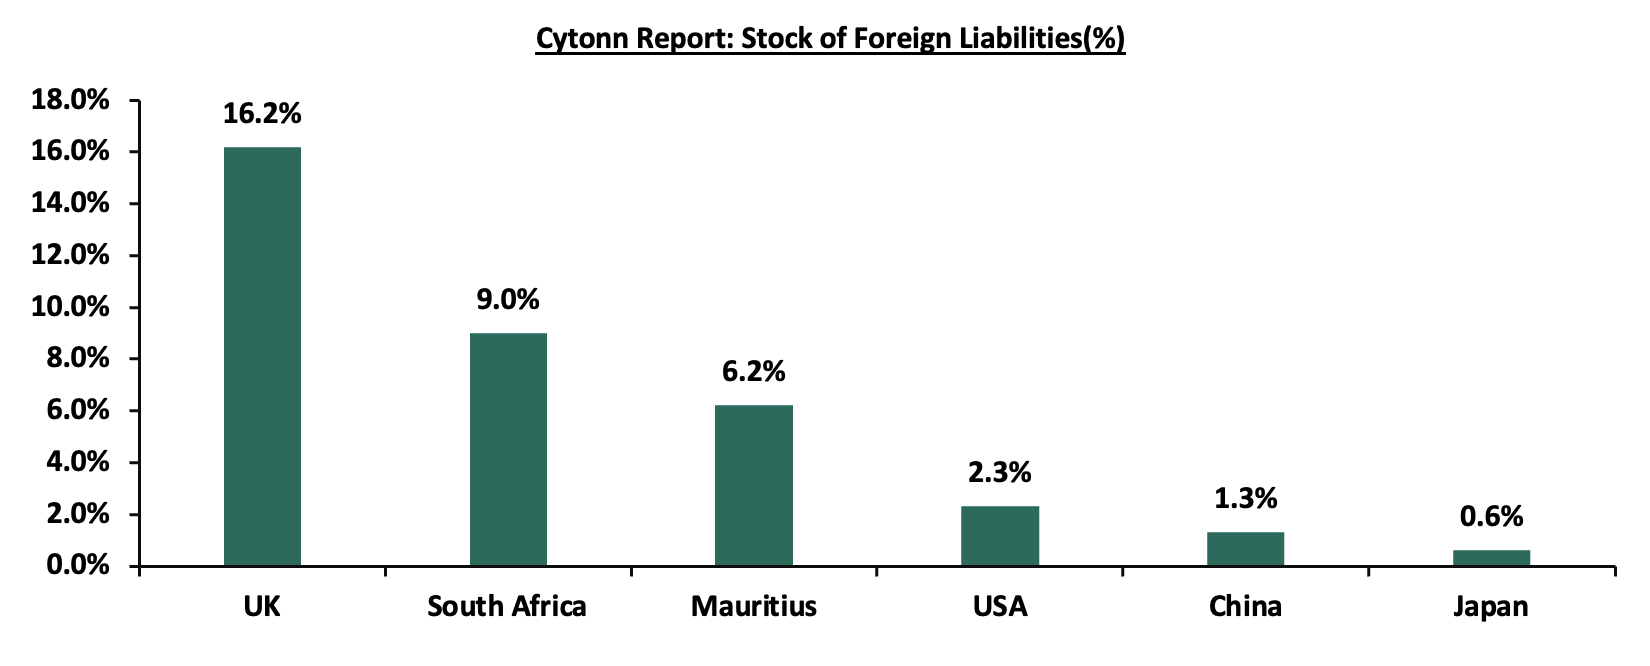
The latest published breakdown of foreign investment by source is the Kenya National Bureau of Statistics (KNBS) Foreign Investment Survey 2024, which covers data to end 2023. The 2025 survey is yet to be published, so the figures predate the record 2025 inflows. Europe accounted for the largest source of investment to Kenya, accounting for 35.0% of Foreign Liabilities in 2023 up from 32.9% in 2022, attributable to 2.6% points increase in the stock of Foreign liabilities in United Kingdom to Kshs 380.0 bn in 2023 from Kshs 309.0 bn in 2022. Africa came in second at 26.4% in 2023 down from 26.6% in 2022 attributable to the 0.9% points decline in Foreign Liabilities in Mauritius to Kshs 144.7 bn in 2023 from Kshs 161.2 bn in 2022. The graph below outlines the percentage of Foreign Liabilities from select countries;
Source: KNBS Foreign Investment Survey 2024.
In terms of sectoral distribution, the finance and insurance sector attracted the highest FDI at Kshs 409.7 bn representing 28.1%, followed by manufacturing which made up 14.8% and ICT which accounted for 12.8%. Meanwhile, wholesale and retail trade saw a decline in FDI liabilities, falling by 1.8% to Kshs 169.8 bn in 2023, from Kshs 172.9 bn in 2022.
Section II: Economic Benefits of FDIs and Challenges to FDI Growth in Kenya
In Kenya, Foreign Direct Investment (FDI) plays a crucial role in driving economic growth and advancing sustainable development. Beyond providing capital, it introduces international expertise that stimulates innovation and strengthens the country’s competitiveness in global markets. Some of the economic benefits of FDIs include:
-
Fueling Economic Growth- FDI is a major source of foreign capital inflow and funds which are used to supplement domestic capital and other earnings from exports. FDIs can deliver job opportunities, technology transfer, skills development and greater access to international markets, all of which raise productivity and growth. Foreign firms also contribute to tax revenues through corporate taxes, payroll taxes and customs duties, giving the government more fiscal space for public spending and debt servicing,
-
Reduced Balance of Payment (BOP) Deficit- FDI strengthens a country’s export capacity by generating higher foreign exchange earnings, which helps finance the current account deficit and supports currency stability,
-
Domestic Currency Support- Increased FDI provides a buffer for the domestic currency by increasing the supply of foreign currency and reducing reliance on external borrowing.
-
Advancing Technology and Productivity- FDI inflows mainly come with the introduction of advanced technology and management practices, which can be used to improve the productivity of the host country, improve efficiency and competitiveness, making the industry more attractive to investors,
-
Increased Job Opportunities- Mostly, FDIs lead to the establishment of new industries which leads to increased opportunities for higher-paying jobs as most of these industries enjoy a global presence. Additionally, this in turn leads to an improvement in the standards of living of the local population, while also fostering skills development through training and knowledge transfer,
-
Development of Local Capital Markets- Growth in FDI leads to increased activity in the capital markets resulting in increased liquidity, deepening of products offerings and depth of the markets. Additionally, the presence of multi-national companies can boost confidence in the market, attracting more foreign investments,
-
Driving Infrastructure Development- Infrastructure is capital intensive and often underfunded in developing economies. FDI provides essential capital for infrastructure projects, which are costly for developing countries to fund on their own. Countries can make use of strategies like Public-Private Partnerships (PPPs), where private investors finance projects like infrastructure, which often leads to better service provision, and,
-
Promoting Sustainable Development- Investment aligned with the Sustainable Development Goals (SDGs) makes up a growing share of global FDI projects. By attracting it, a country can benefit from a faster transition to renewable energy, green infrastructure, and sustainable buildings, which are essential for long-term economic health.
Despite the obvious benefits of a vibrant FDI sector, Kenya’s FDI remains lumpy and concentrated, and the 2025 record sits alongside persistent constraints. Some of the challenges to FDI growth include;
-
High Levels of Corruption - The constant corruption scandals are a significant deterrent to FDI in Kenya as investors see it as the increase in the cost of doing business as well as a reduction of operations efficiency. According to Transparency International 2025 Corruption Perceptions Index, Kenya was ranked 130th out of 182 economies after scoring 30 out of 100, which was worse compared to other peer economies like Tanzania and Ethiopia, which scored 40 and 38 respectively, with the global average being 42,
-
Weak Foreign Portfolio Flows – Higher global rates and risk-off sentiment have kept foreign investors out of the equities market. Foreign investors remained net sellers, with a net outflow of USD 92.9 mn compared to USD 16.9 mn in 2024, even as the NSE All Share Index rose 52.5%.
-
High taxes - The Finance Act 2023 doubled VAT on fuel to 16.0% from 8.0%, raising input costs. Pump prices now carry VAT at 8.0% under a Government policy to cushion consumers, but that relief could be withdrawn. The Finance Act 2026 cuts both ways for foreign investors. It introduces a 15.0% repatriation tax on non-resident mining and petroleum firms from January 2027 and a 30.0% tax on non-resident landlords’ gross rent. It also repeals the 15.0% corporate rate for residential developers and extends capital gains tax to non-residents’ sales of Kenyan-linked shares. These are partly offset by a lower 30.0% corporate rate for non-resident extractive firms, down from 37.5%, and by incentives for large investments. Real estate and extractives investors therefore face higher costs, while large manufacturing and energy-storage investors gain, and frequent annual changes make taxes harder to predict.
-
Underdeveloped Infrastructure and Security Concerns - Despite the deliberate effort to develop infrastructure by the former governments, some areas remain inaccessible as a result of poor roads. Additionally, Kenya still faces security concerns in some areas which can limit foreign investments into the country.
-
External shocks and softer remittances- S&P cut its 2026 Kenya growth forecast to 4.9% from 5.1%, citing higher energy, fertilizer and import costs linked to the Middle East conflict. Remittances, a key source of foreign exchange, have also softened, falling 1.1% to USD 5,023.2 mn in the 12 months to October 2026, from USD 5,081.6 mn a year earlier.
Section III: Recommendations
Foreign Direct Investment (FDI) plays a crucial role in driving economic growth and development, especially in emerging markets such as Kenya. Strengthening FDI inflows requires creating an environment that both attracts and sustains investors. Kenya’s strategic location as a hub for East and Central Africa, combined with its expanding consumer base, presents significant opportunities. Realizing this potential calls for a comprehensive strategy, and additional measures are needed to support FDI growth. Some of the steps the government can consider include:
-
Deepen our Capital Markets – The government should strengthen capital markets by adopting policies that attract foreign investors, simplifying regulations, and rolling out initiatives that promote investor confidence. Encouraging more companies, especially in sectors like technology, manufacturing, and renewable energy, to list on the stock exchange would deepen the market. A stronger capital market not only draws foreign capital but also improves liquidity and broadens investment choices.
-
Improve Diaspora Funding - Remittances have softened. Over the 12 months to October 2026 they fell 1.1% to USD 5,023.2 mn, from USD 5,081.6 mn. Against this backdrop, the government can expand diaspora inflows by formulating investment-friendly policies, offering tax holidays on investments made back home and issuing diaspora-specific bonds.
-
Improve the Ease of Doing Business – The government can make it easier to start and run businesses by cutting red tape and simplifying procedures. This includes digitizing services, introducing online registration platforms, and lowering the time and cost of securing permits and licenses. Offering incentives and support to small and medium-sized enterprises (SMEs) would further strengthen the business environment and help attract both domestic and foreign investment,
-
Key Infrastructure Development – Good infrastructure makes a country more appealing to foreign investors. Investing in transport networks can ease the movement of goods and people, lowering operational barriers for businesses. At the same time, with rapid advances in technology, the government should prioritize digital infrastructure such as high-speed internet and reliable communication systems to enhance connectivity and give businesses better access to global markets. Additionally, there is a need to leverage more on innovation, digitization, and product development in the capital markets and larger investment environment. This will allow quick access to investment avenues by investors and open up the markets to retail investors, reduce the lead time between making an investment decision and its practical execution, and reduce costs incurred during physical applications,
-
Operationalize Special Economic Zones (SEZs) – Kenya should place greater focus on Special Economic Zones (SEZs) as a critical driver of manufacturing, industrialization, and investment-led social transformation. For instance, Tatu City is Kenya’s first operational Special Economic Zone, providing reduced corporate taxes, zero-rated VAT, and import duty exemptions, among other benefits. Other SEZs under development include the Dongo Kundu Special Economic Zone in Mombasa, the Naivasha Special Economic Zone, and the Konza Technopolis,
-
Public-Private Partnerships (PPPs) – Collaboration with the private sector allows the government to share risks, mobilize extra financing, and leverage private expertise in project execution. Expanding Public-Private Partnerships (PPPs) beyond infrastructure into areas like healthcare, education, and tourism can open new investment avenues, enhance service delivery, generate jobs, and stimulate economic growth, thereby strengthening Kenya’s position as an investment hub,
-
Developing Kenya's Key Sectors – Kenya should focus on sectors with high growth potential that give it a competitive edge in Sub-Saharan Africa by offering tax incentives and streamlined regulations for specific sectors. The sustainable energy sector is especially promising, supported by established geothermal generation and wind power projects in Lake Turkana, aligning with the current investor emphasis on SDGs. Other priority areas for investment include agriculture and agro-processing, healthcare, education, financial services, ICT, infrastructure, manufacturing, real estate, construction, and tourism, and,
-
Ensure a Strong and Conducive Regulatory Framework – A clear and transparent regulatory framework gives investors the assurance and security needed to commit capital. It is therefore important that investors fully understand the rules governing their operations and have confidence in the stability of future regulations. This requires regular reviews and updates of existing laws and regulations to address existing gaps with regard to the changing business environment.
Section IV: Conclusion and Our Outlook
Kenya’s FDI inflows had long lagged those of its peers, but 2025 changed that picture. Inflows rose 37.7% to a record USD 3,200.0 mn, from a revised USD 2,324.0 mn in 2024 which vindicated the expectation in our earlier edition of strong growth. UNCTAD credits investment reforms and the country’s renewable-powered digital infrastructure pipeline, and the same factors that supported the increase have also lifted sentiment more broadly. S&P upgraded Kenya’s sovereign rating to B from B- in August 2025, and affirmed it with a stable outlook in August 2026. Earlier in the year, in January 2026, Moody’s upgraded Kenya to B3 from Caa1 and moved the outlook to stable. Fitch affirmed its B- rating with a stable outlook in January 2026. The outperformance should not be overstated, however, since Kenya still ranks third in East Africa behind Ethiopia and Uganda, and at about 2.4% of GDP its FDI intensity is only moderate.
We are more cautious for 2026 as the 2025 figure was a record built partly on a small number of large projects, so a moderation from this base would not be surprising. Several headwinds point that way. UNCTAD describes the 2026 escalation of conflict in the Middle East as a major adverse shock to global investment, and S&P has cut its 2026 growth forecast for Kenya to 4.9% from 5.1%, citing higher energy and fertilizer costs. Diaspora remittances, a key source of foreign exchange, have also stopped growing. They fell 1.1% to USD 5,023.2 mn in the twelve months to October 2026, from USD 5,081.6 mn a year earlier. Fiscal pressure ahead of the 2027 general election adds to this, with S&P warning that the deficit could widen to 7.1% of GDP in FY2026/27. Tax changes under the Finance Act 2026, including a new 15.0% tax on repatriated income for mining and petroleum investors from 1 January 2027, will also weigh on some foreign investors.
The medium-term case nevertheless remains supportive. Reserves of USD 14.6 bn, equivalent to 5.9 months of import cover, and a shilling that has been stable around Kshs 129 to the dollar since the start of 2025 give investors more certainty on currency risk than at any point since 2023. The Finance Act 2026 also retained and expanded incentives for large-scale investors, including VAT exemptions and accelerated capital deductions. The digital and clean-energy pipeline that UNCTAD highlights is a further support, and policy moves such as the 2023 removal of the 30.0% local ownership requirement for foreign ICT companies and the UAE Comprehensive Economic Partnership Agreement are expected to open flows into energy, water, agriculture, health, ports, airports, logistics, human resources and ICT.
Corruption, tax predictability and the cost of electricity remain the main concerns for foreign investors. Kenya scored 30 out of 100 on Transparency International’s 2025 Corruption Perceptions Index, and 70.0% of investors in the KNBS survey named electricity the costliest business-enabling service. These are the areas that will determine whether 2025 proves to be a turning point or a high-water mark. Readers should also note that UNCTAD revises its estimates, as the restatement of Kenya’s 2024 figure shows, so the 2025 number may change.
Disclaimer: The views expressed in this publication are those of the writers where particulars are not warranted. This publication, which is in compliance with Section 2 of the Capital Markets Authority Act Cap 485A, is meant for general information only and is not a warranty, representation, advice or solicitation of any nature. Readers are advised in all circumstances to seek the advice of a registered investment advisor.
- Talk to us
- Kenya
- P.O Box 20695 - 00200, Nairobi, Kenya
- Cell +254709101200
- Tel +254709101200
- WhatsApp +254741676635
- United States
- +254709101200
- DOWNLOAD OUR APP
-
- Kenya
- 8th Floor, Pinetree Plaza, Kaburu Drive, Ngong Road, Nairobi, Kenya
- USA
- Suite 1150, 1775 Eye Street NW, USA, Washington DC 20006, USA
- Investments
- High Yield
- Private Equity
- Real Estate
- Real Estate
- RiverRun Estates
- Cytonn Towers
- The Ridge
- Taraji Heights
- The Alma